

Creator of commercial vehicle values and market analysis
Joined September 2014
- Tweets141
- Following86
- Followers76
- Likes85


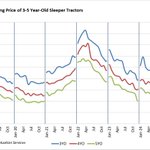


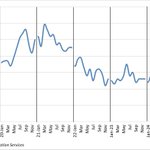


Class 8 retail pricing increased in late summer and held strong through September. More details here:
jdpowervalues.com/article/oc…
Aug. used sleeper market was generally healthy, particularly at auctions and wholesale channels. New truck orders and deliveries are unusually far apart, pointing to an interesting Q4. Read more here:
jdpowervalues.com/article/se…
The latest JD Power Specialty Vehicles Market Insights reports provide detailed analysis of pricing movements and demand trends across the Powersports, Marine, and RV segments in the second quarter of 2026. Click below to view:
jdpowervalues.com/specialty-…
1H Class 8 pricing and volume ended on a positive note. Increased new truck production means higher deliveries and an uptick in trades. Read more here:
jdpowervalues.com/article/ju…
After a strong Q1, the used Class 8 market is on cruise control. The market will continue to strongly favor low-mileage trucks as the supply of higher mileage units increases with pre-buy activity in upcoming months. Read more here:
jdpowervalues.com/article/sa…
Sustained freight rate improvement, healthy retail sales, and stable pricing collectively signal that the used truck market has cycled back into positive territory. May data here:
#trucking #Assetmanagement #usedtrucks
jdpowervalues.com/article/ma…
Class 8 retail sales volume roared back in March to the highest level in almost 5 years. Pricing remained stable, suggesting buyers are more confident about their prospects going forward. More data and commentary here:
jdpowervalues.com/article/ap…
In the March edition of Guidelines, we track lower selling prices in February and provide color behind the movement. Download here:
#trucking #fleets
lnkd.in/eZSkxYYp
The 2026 used truck market opened up strong in Jan. Auction and retail pricing increased over December, and retail volume was very healthy (by recent standards) for the 2nd month in a row. Click below to download our Feb. Guidelines Market Report:
hub.jdpower.com/hubfs/Files/…
Chris Visser retweeted

UTA Truck Talk Podcast EPISODE 7 — J.D. Power Market Update
with Chris Visser, Director of Specialty Vehicles
Podcast page ➡️ uta.org/Podcast-UTA-Truck-Ta…
YouTube ➡️ youtube.com/watch?v=rHX-8zXI…
Subscribe to UTA YouTube Channel: youtube.com/@UsedTruckAssoci…
#utapodcast #UTAtrucktalk

In the January edition of our Guidelines monthly market report, we track auction and retail volume and selling prices over 2025, and provide an outlook for 2026. Click here to download:
#Assetmanagement #fleets #trucking
jdpowervalues.com/article/ja…
As the used Class 8 market enters its seasonal lull, we’re looking towards next year for active truck utilization and capacity to adjust back to where they eventually kick the cycle back into the acquisition phase. Data and commentary here:
#trucking
jdpowervalues.com/article/au…
October Class 8 auction pricing was down 6% MoM but up 2% YoY. Pricing is about halfway between 2018 (strong) and 2019 (weak) markets in real numbers. Any recovery will be supply-driven (fleet downsizing), and require the goods economy to hold up.
#FleetManagement #class8

Since July, retail depreciation for sleeper tractors has averaged 2.1%. This is a notable change from stable pricing in 1H. On the bright side, dealers are retailing more trucks than last year. October Guidelines available here:
jdpowervalues.com/article/cl…
At Class 8 auctions in August, volume ticked up while pricing moved down. 4-6 year-old sleeper tractors averaged 4.6% lower pricing than July, but only 0.4% lower than August 2024. Average monthly depreciation in 2025 is now up to 2.1%. More data and insight next week.

In July, Class 8 sleeper retail selling prices decreased M-o-M for the first time since December 2024. However, dealers sold more trucks than in June. Y-o-Y comparisons remain positive. Click the link below for our full August market update:
jdpowervalues.com/article/au…

3-year-old sleepers finally made an appearance at auctions in June. Our July Guidelines provides data on the auction and retail channels, along with commentary. Click here for the download page:
jdpowervalues.com/article/ju…
Class 8 sleeper retail pricing increased for the 5th month in a row in May, albeit less than 1%. Retail sales per dealership also ticked up to 3.2 trucks - the best result since June 2023.
More data in the June edition of Guidelines, available here:
jdpowervalues.com/article/ma…

Class 8 auction pricing pulled back in May, with late-model sleepers bringing 3.7% less money MoM. We’re also seeing fewer 3-year-old trucks than we’d typically expect by midyear. Some end users are likely holding off on trading for new.

Supply was tighter and pricing was higher at April Class 8 auctions, as end users traded out of their older trucks to take advantage of what could be the last of pre-tariff, pull-ahead freight activity, plus get ahead of higher pricing. More here:
jdpowervalues.com/article/cl…
