
An enthusiastic young man with a sixth grade education and an abiding love for Special Purpose Acquisition Companies
Joined September 2020
- Tweets2.5K
- Following254
- Followers642
- Likes7.7K






Pinned Tweet
Mmmmm... delicious crow... @CEOAdam


So amusing. Narrow-minded call our Hycroft investment… “stupid”…“idiotic.” AMC so understands how to raise cash and stretch out debt. Eric Sprott understands gold & silver. Add in a very low price for our shares/warrants. Tons of crow eating ahead, and it won’t be by me! #HaHa

LOLOLOLOLO

Wow you are a moron. There is literally zero chance of $2 per share.
Readers added context they thought people might want to know
It hit $2/share
x.com/MebFaber/statu…
Global MNOs need $ASTS to win if they are going to compete with Starlink. And at the current price $ASTS is being valued barely more than the value of its spectrum assets

$ASTS | Deutsche Bank:
We are upgrading ASTS to Buy and maintaining our $93 PT. The stock is down ~65% from its all-time high in May. We had downgraded the stock in May after the New Glenn launchpad explosion that introduced a material delay in ASTS’ launch plans, combined with valuation concerns. However, we believe now is an opportune time to become more constructive given the recent stock-price weakness, a number of positive developments/catalysts that we think have gone under the radar, and spectrum value that we estimate now comprises all but $10 per share in ASTS’ EV. Furthermore, we think the -10% move on Friday was misguided since the 800 MHz spectrum SpaceX will be acquiring doesn’t make SpaceX more competitive with ASTS as an MNO partner for D2D, and ASTS isn’t targeting direct-to-consumer (for which SpaceX will primarily use the 800 MHz).
We see a number of positive developments/catalysts for ASTS in the near term:
We believe it is increasingly likely that T-Mobile will switch from Starlink to ASTS as its D2D partner (through the JV). Roughly coincident with the timing of the announcement that AT&T, Verizon, and T-Mobile reached a definitive agreement to form a D2D JV on Oct. 1; T-Mobile appears to have removed many (but not all) references to Starlink from its website. Furthermore, SpaceX’s efforts to compete with the Big 3 MNOs in mobile continues to antagonize the Big 3 (and shrink their market capitalizations), pushing them even closer to ASTS. SpaceX’s announced purchase of 14 MHz of 800 MHz spectrum from Grain Management on October 8 was the latest shot across the bows of the Big 3, leading to a 10-13% decline in their stock prices on Friday (just the latest SpaceX-driven market-cap destruction for the telcos).
The Space Development Agency (SDA) sent a letter to the National Telecommunications and Information Administration (to be then forwarded to the FCC) in September expressing support for ASTS’ request for Temporary Authority to conduct testing of pulsed radiolocation capabilities in the 902–928 MHz band using its in-orbit BlueBird satellites. The letter names ASTS as a subcontractor and stresses the national security importance of testing these capabilities (which appear to be sensing related). We believe this is indicative of continued progress by ASTS in expanding its government contract base, a revenue opportunity that seems to be expanding every day.
The preliminary selection of ASTS (along with Rakuten) for the Japan LEO project took a step forward when the October 5 Joint Statement on the U.S.-Japan Technology Prosperity Deal specifically “welcomed Japan’s Rakuten Group and the U.S.-based AST SpaceMobile cooperation for the development and deployment of Low Earth Orbit (LEO) satellite infrastructure”. We view this as a sign that the official J-LEO authorization could be coming soon. If/when approved, it means the Government of Japan will fund up to $1B of capex for ASTS’ satellite constellation in exchange for sovereign use and control of a number of satellites while they are able to provide coverage to Japan. This “up to $1B” is not reflected in our current valuation, even though it would represent essentially free capital, significantly improving ASTS’ liquidity position.


Pretty good company I’d say
$BCCQ


Ursa Major is proud to be selected for @NSTXL's Next Generation Hypersonics for the @DeptofWar!
Learn more at: nstxl.org/opportunity/projec…

Howard Roark retweeted

$CCXI did Digit kill somebody during the presentation?
Um, this is more than a full year’s worth of revenue… $BCCQ
The @USNavy has awarded Ursa Major $137M to develop and qualify advanced solid rocket motors for the Compact Air-to-Air Missile (CAAM) and Naval Modular Missile (NMM) programs.
“Production is the bottleneck in missile programs right now, and that's the part we've been building for.” Jason Meredith, President, Ursa Major.
Leveraging our advanced manufacturing approach and growing energetics capacity, Ursa Major is accelerating the development and delivery of tactical motors designed for production at scale.
Read the full release at the link in the replies.
Howard Roark retweeted
$BEAG / REDLattice could be a winner. Cyber end markets are hot, real rev ($260 million TTM) growing 25-30%, 80% gross margin, cash flow positive. Guessing they do $90 million EBITDA next year, implying 13x '27 EV/EBITDA. I'll hold that through close
$BEAG / REDLattice could be a winner. Cyber end markets are hot, real rev ($260 million TTM) growing 25-30%, 80% gross margin, cash flow positive. Guessing they do $90 million EBITDA next year, implying 13x '27 EV/EBITDA. I'll hold that through close

As of yesterday's analyst day, $ATII still saying $40 million of sales in '26. But H1 actual was $4 million, so the projections are stale, right? They are going to come public and immediately miss? Wish they had clarified at the event @ForgeNano
Agree with this. Not many ways to play the humanoid robotics theme. $NTWO has been overlooked so far but is interesting when you dig in. Already generating real revenue ($12 million last year at 65-70% gross margin) and the investor presentation implies they are looking for bookings to almost triple this year to $35 million. I don't love the sweetheart deal the PIPE investors got (effective $6.81/share), but hey if @mcuban comes out with an endorsement it would go a long way

Trump campaigned on ending Middle East forever wars. Also cheap gas. And he attacked Powell for not lowering interest rates. Then he started a new Middle East forever war that spiked gas prices, which is going to force his new hand-picked Fed Chair to RAISE interest rates.
Both entertaining and ironic. I'd say Elon's theory is confirmed.

Howard Roark retweeted
Don't let Obama buy the election by handing out unlimited free money to states.
Howard Roark retweeted

$SKM has 4x more Anthropic exposure per dollar of market cap than second place $ZM.
Yesterday, SKT’s CEO Jung Jae-heon confirmed the company participated in Anthropic's Series H and has no plans to sell ahead of the IPO.
Strip that Anthropic stake and $SKM's core telco trades at approximately 6.1x EV/EBITDA, the cheapest name in the global peer group.
If Jensen's bet on telecom as critical AI infra pans out, $SKM's goldmine goes far beyond its early bet on Dario and co.

Fantastic risk/reward on $BCCQ / Ursa Major. Company sits at the intersection of 3 trends:
- massive missile replacement cycle (Ukraine, Iran)
- DoD push for second source suppliers
- emergence of non-traditional "new defense" companies (Anduril, etc)
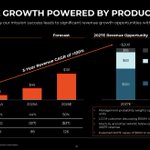
Yes its a SPAC but it is not like the others. 100%+ rev growth trajectory:
- FY24A $19mn
- FY25A $45mn
- FY26E $101mn
- FY27E $200mn (majority already in backlog)
With a $2.8bn new business pipeline
Private peer Castelion provides an interesting valuation comp. Castelion just raised a round at a $13bn billion vs $BCCQ at $1.6bn pre-money
Stock closed Friday at $9.99, a discount to the current NAV of $10.07 (will be $10.25 by the time the deal closes in Q1). Catalysts? The investor presentation lists 6 near-term contract opportunities in the $50-300mn range


$BCCQ valued at $1.6 billion and sitting at NAV. Meanwhile peer Castelion just raised a round at a $13 billion valuation 🤔
castelion.com/news/series-c/


Ursa Major / Bleichroeder Acquisition III deal overview
Aerospace and defense company building hypersonics, solid rocket motors and space mobility systems
$1.7 billion enterprise value
$350 million PIPE
Closing Q1 2027
PR: sec.gov/Archives/edgar/data/…
IR deck: sec.gov/Archives/edgar/data/…
Disclosure: Long $BCCQ shares + warrants in $ARB.to
