





Pinned Tweet
Independent, daily GPU rental reference rates across Hyperscaler, Neocloud & Marketplace.
No positions. Built from verifiable published prices.
Built so lenders, rating agencies & counterparties reference the same series.
ccir.io/home


Another week and more posted on demand rate increases worldwide (and new listings for B200)
E2E Networks (India)
H100 $2.69 → $3.99
H200 $3.99 → $5.29
Crusoe (U.S. and Europe)
H100 $3.90 → $4.50
H200 $4.29 → $5.40 (Europe)
B200 newly listed at $8.50
Lyceum (Europe)
B300 $7.99 → $11.09
B200 $6.49 → $8.79
H200 $4.49 → $6.19

GPU providers have been raising prices around the world for short term compute over the last few weeks. Some of the moves since Sep 10:
U.S.
• AWS Capacity Blocks: +15% on every chip
• Nebius: H100 +17%, H200 +20%, B200 +19%, B300 +21%
• RunPod Secure Cloud: H100 +14%, H200 +15%, B200 +18%, B300 +14%
• GMI Cloud: H100 +30%, H200 +23%, B200 +25%
EU
• Verda (Finland): H100 +20%, H200 +27%, B200 +20%, B300 +23%
• Nebius: H100 +17%, H200 +20%, B200 +19%, B300 +21%
• Gcore: H100 +20%, H200 +16%
• RunPod Secure Cloud: H100 +14%, H200 +15%, B200 +18%
India
• JarvisLabs H100 +30%, H200 +15%
• NeevCloud: H100 +19%, H200 +19%
• RunPod Secure Cloud: H100 +14%
A few other providers across geos + < 10%
AWS and Google Cloud spot
• AWS U.S. spot, typical zone: H100 +43%, H200 +40%, B200 +42%, B300 +52%
• Google Cloud spot: H100 +13%
In addition to the spot end commitment prices (one month to a year) rose with hourly prices at RunPod, Verda, JarvisLabs and NeevCloud.
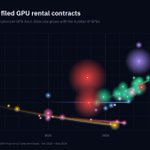
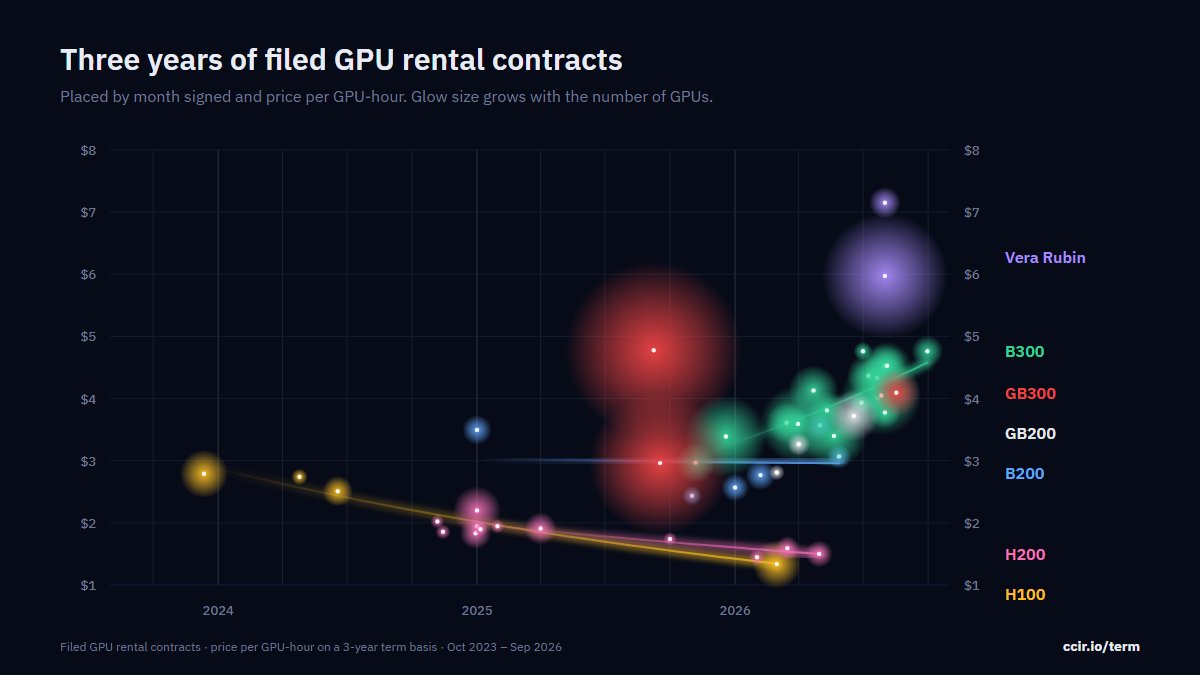
First couple Vera Rubin deals rolling into our contract rate vintage charts. Small sample size noted here but try and get these rates comparable across tenor, prepayments, bundling for users to compare where the market is for longer term GPU contracts over time.
Since Sep 14, here are the primary moves on Vercel's AI Gateway m/m
Flagship models (Claude Opus, GLM 5.3, Kimi K3, Grok): 5% → 17%
• Claude Opus 5.5: outside the top 10 → 6.5%
• GLM 5.3: outside the top 10 → 6%
• DeepSeek V4.1 Flash: 61% → 28%
ccir.io/tokens


GPU providers have been raising prices around the world for short term compute over the last few weeks. Some of the moves since Sep 10:
U.S.
• AWS Capacity Blocks: +15% on every chip
• Nebius: H100 +17%, H200 +20%, B200 +19%, B300 +21%
• RunPod Secure Cloud: H100 +14%, H200 +15%, B200 +18%, B300 +14%
• GMI Cloud: H100 +30%, H200 +23%, B200 +25%
EU
• Verda (Finland): H100 +20%, H200 +27%, B200 +20%, B300 +23%
• Nebius: H100 +17%, H200 +20%, B200 +19%, B300 +21%
• Gcore: H100 +20%, H200 +16%
• RunPod Secure Cloud: H100 +14%, H200 +15%, B200 +18%
India
• JarvisLabs H100 +30%, H200 +15%
• NeevCloud: H100 +19%, H200 +19%
• RunPod Secure Cloud: H100 +14%
A few other providers across geos + < 10%
AWS and Google Cloud spot
• AWS U.S. spot, typical zone: H100 +43%, H200 +40%, B200 +42%, B300 +52%
• Google Cloud spot: H100 +13%
In addition to the spot end commitment prices (one month to a year) rose with hourly prices at RunPod, Verda, JarvisLabs and NeevCloud.
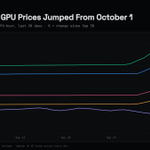
Well had noted late last week that AWS spot had been flat since mid August; No more. Prices in U.S. last few days:
As noted previously there is also the announced increase for reserved GPU block prices of 15% coming October 7 across A100 - B300
ccir.io/discovery


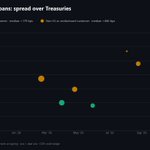
GPU-backed debt opened Q4 with Lambda's $1B fixed-rate loan on Oct 1 - rated Baa1 / A (low). It priced 160 basis points over the Treasury of the same term.
Chart plots the past year of fixed-rate GPU deals by their spread over Treasuries at signing.
(The three Valor leases (triangles) are to xAI with the 2 most recent being after SpaceX acquisition and all prior to June investment grade rating)

Happy Q4! Some quick looks at what we are seeing in compute
->Reminder that comments to the CFTC on compute derivatives are due by October 20, just under three weeks away.
->Signed term contracts: We model every disclosed contract onto a 3 yr tenor basis. From November '25 B300 rates up ~30% this year while B200 down slightly and Hopper deals down 20% (most recent Hopper deals from Q1) (ccir.io/term)
->In spot market - interruptible grade product from AWS: all chips were up in Q3 (B300 up 60%). HOWEVER, all chips pretty flat since mid Aug. (ccir.io/discovery#map)
->Price changes coming: Nebius raised on-demand GPU prices 17% to 21% today across H100 - B300 and AWS increasing its reserved GPU block prices 15% on October 7 across A100 - B300.
->Nebius spot goes market-driven on October 8. Each GPU type and region gets its own price set from capacity and demand and updated as often as every 15 minutes.
-> Tokens served through Vercel router: For last couple months the trend has been hard to open weight but in the last couple days of September, traffic did shift a bit back to a few frontier models. Open weight share from 73% to 58%. Clause Opus 5.5 and GPT-6 Luna each roughly doubled their share. (ccir.io/tokens)


What has happened to Neocloud fleets when they lost a major customer?
-> Northern Data took ~3 quarters to re-let 22,000 GPUs, at ~70% of prior yield.
-> Applied Digital took 5.5 months to re-let 2,048 H100s, to its remaining tenant on a mtm contract at a lower yield.
-> WhiteFiber sold its H200s in Q1 2026 at ~$25.9k each (~90% of cost).
These are 3 of 38 cases we found in filings, court records and press reports since 2022. Our write-up:
ccir.io/research/gpu-fleet-d…

Since March, 11 B300 contracts have been publicly disclosed. Three-year rates rose from:
~$3.39 per GPU-hour to $4.23 (up 25%)
On a three-year contract for 10,000 GPUs that is about $220 million.
ccir.io/research/b300-contra…

The CFTC extended its review of CME's H100 and B200 rental-index futures by 45 days to November 9 - after the comment period closes Oct 20.
The letter cites "novel or complex issues." It ties the extension to the open request for comment, which covers the factors "relevant to the listing for trading of derivatives with compute as the underlier."
(CME had targeted an October 5 first trade date)
Letter: cftc.gov/filings/documents/2…
Comment Tracker: ccir.io/research/compute-der…