

40-Yr Markets Veteran | Behavioral Econ | Seasoned Biotech Investor | Special Situations | Value/Trend Inflections | Founder/CEO (Ret.) | PM | Opinions only-NFA
Inland Northwest
Joined April 2023
- Tweets4.5K
- Following91
- Followers1.1K
- Likes4.5K


Pinned Tweet
"The stock market is never obvious. It is designed to fool most of the people, most of the time."—Jesse Livermore.
After almost four decades in this game, it’s a reminder I come back to often, and one every serious market professional eventually learns. This business rewards process, discipline, and execution—not hype or guesswork. The market’s job is to challenge your conviction; your job is to stay grounded in the work.
With that said, I invest heavily in institutional-grade research platforms and technical tools to ensure every thesis is backed by high-signal data. My approach is a synthesis of advanced technical analysis and deep forensic due diligence. I leverage this framework to challenge consensus and discover the disconnect between market sentiment and data-driven reality.
Hope is not a strategy. I trade on a repeatable process designed to put the mathematical odds in my favor. Tune out the noise. Stick to the plan. Focus on execution.
Wishing everyone continued success and good trading ahead.
BluntForceOptions retweeted
$QQQ just lost the cloud on bearish momentum
The 50-week EMA is calling... 😬

$FNUC We tore the fundamental wrapper apart when this was trading at $1.80 ish. It's since been obliterated down to $0.64. I just stepped in with a 10,000-share starter position today.
To be clear... my thesis on the corporate opacity hasn't changed. This is purely a mechanical mean-reversion trade.
The broad micro-cap flush has completely pegged the indicators here. The daily RSI (14) is sitting at a mathematically washed-out 14.64, and Slow Stochs are buried at 2.84. We're in extreme structural oversold territory.
And if you look at the historical price action, any major leg down has resulted in a swift relief rally to test the descending 50-day SMA. That 50 SMA is currently parked at $1.36. I'm playing strictly for that reversion, which represents a 110%+ move from current levels. The fundamentals are still a black box, but the asymmetric math on this setup is too heavy to ignore, IMO.
Then there’s the catalyst. The Engo Valley maiden resource was guided to mid-Q3 2026 and still hasn’t landed, so it’s live at any point. At $0.654, the entire co is a ~$23.6M MC with Pine Ridge 100% owned, Tallahassee’s 52.2 Mlbs, the Ubaryon stake alongside Urenco, and Kadmos all in there. A positive print into a float this flushed out has nothing left to sell into it. That’s gap risk pointed up, and it is not priced here. Just my two cents and NFA. Giddy up!

BluntForceOptions retweeted

$ELTX: One of our #ESMO2026 watchlist catalysts just reported.
Phase 2 ELI-002 7P pancreatic cancer update:
• Primary DFS endpoint misse already disclosed in June.
• New subgroup data: DFS HR 0.51 in ctDNA-negative patients; 0.57 in ctDNA-positive patients.
📊Shares pared earlier losses to −1.5%
Our pre-ESMO Prob/Mag scenarios below 👇
Next watch: Phase 3 development plans.

$MGNX Stepped in and bought a half position at $2.31. Here’s why:
MacroGenics delivered at ESMO this morning. Interim Phase 1 data for MGC026, its B7-H3 antibody-drug conjugate, showed durable responses across multiple tumor types and a clean safety profile. Based on these results, the co plans to open a front-line head and neck cohort combining MGC026 with Keytruda in early 2027. This is a positive readout, and management executed exactly what it laid out back in July. The stock is down ~36% anyway.
Here's what was actually reported.
• SCCHN cohort (heavily pretreated, median 3 prior lines): 27% best overall response, 6 of 22. That's 4 confirmed PRs and 2 unconfirmed. Disease control 64%.
• Dose escalation, at least 6 mg/kg across 10 tumor types: 29% confirmed ORR, median duration of response 10.2 months.
• Zero ILD, pneumonitis or ocular toxicity across all 85 patients treated. For an exatecan-payload ADC, that's the headline that matters.
• No treatment-related discontinuations in SCCHN. Grade 3+ events were mostly anemia and neutropenia, described as manageable and reversible.
• Stage 2 of the SCCHN cohort is enrolling, with updated data expected mid-2027.
The bal sheet is where it gets interesting, IMO...
• Pro forma cash of $327M as of June 30, after the Bora manufacturing sale and the Sanofi and Gilead milestones.
• 63.65M shares outstanding. That's $5.14 per share in pro forma cash.
• At ~$2.34, the market cap is ~$149M. You're paying roughly 45 cents on the dollar for the cash alone.
• Runway guided through 2028, so no near-term raise is needed to reach the next readout.
The way I see it, the tape sold the 2 unconfirmed PRs and the heme tox line, ignored the safety profile that differentiates this ADC, and ignored a cash pile worth more than double the market cap. That's the kind of disconnect I want to step into.
Regarding the tape... a gap through the 20, 50, 100 and 200-day on 8x avg volume, with daily RSI at 26. That's capitulation-grade selling into a positive data release.
Levels I'm watching: today's low in the $2.25 area, then the $2.00 to $2.20 base the stock built before the March breakout. The 200-day sits overhead near $3.40, and yesterday's close of $3.63 is the gap fill.
Bottom line: the event risk is behind it, the cash isn't going anywhere, and the market is pricing the pipeline near zero. That's where asymmetric setups come from.
Just sharing my work. Please check everything yourself. NOT financial advice.


$AIXI ripping hard in the premarket 🚀

$AIXI refuses to stay down... nine lives on this bugger. Every time the market writes the obituary, it shakes off the flush and fights back to $3.00+. With this structure, honestly, nothing would surprise me... a complete breakdown or a vertical squeeze to $40 would both fit right into the script. 🚀
$SPCX scores a double-upgrade at Phillip Securities to Buy from Sell, lifting their PT 233% to $250 on a 161% YoY Q3 rev blowout ($14.6B). Wall Street consensus sits at a Strong Buy with an avg PT of $250 (+72.7% upside), backed by FY27 rev estimates surging 201% to $132B. Textbook institutional capitulation.

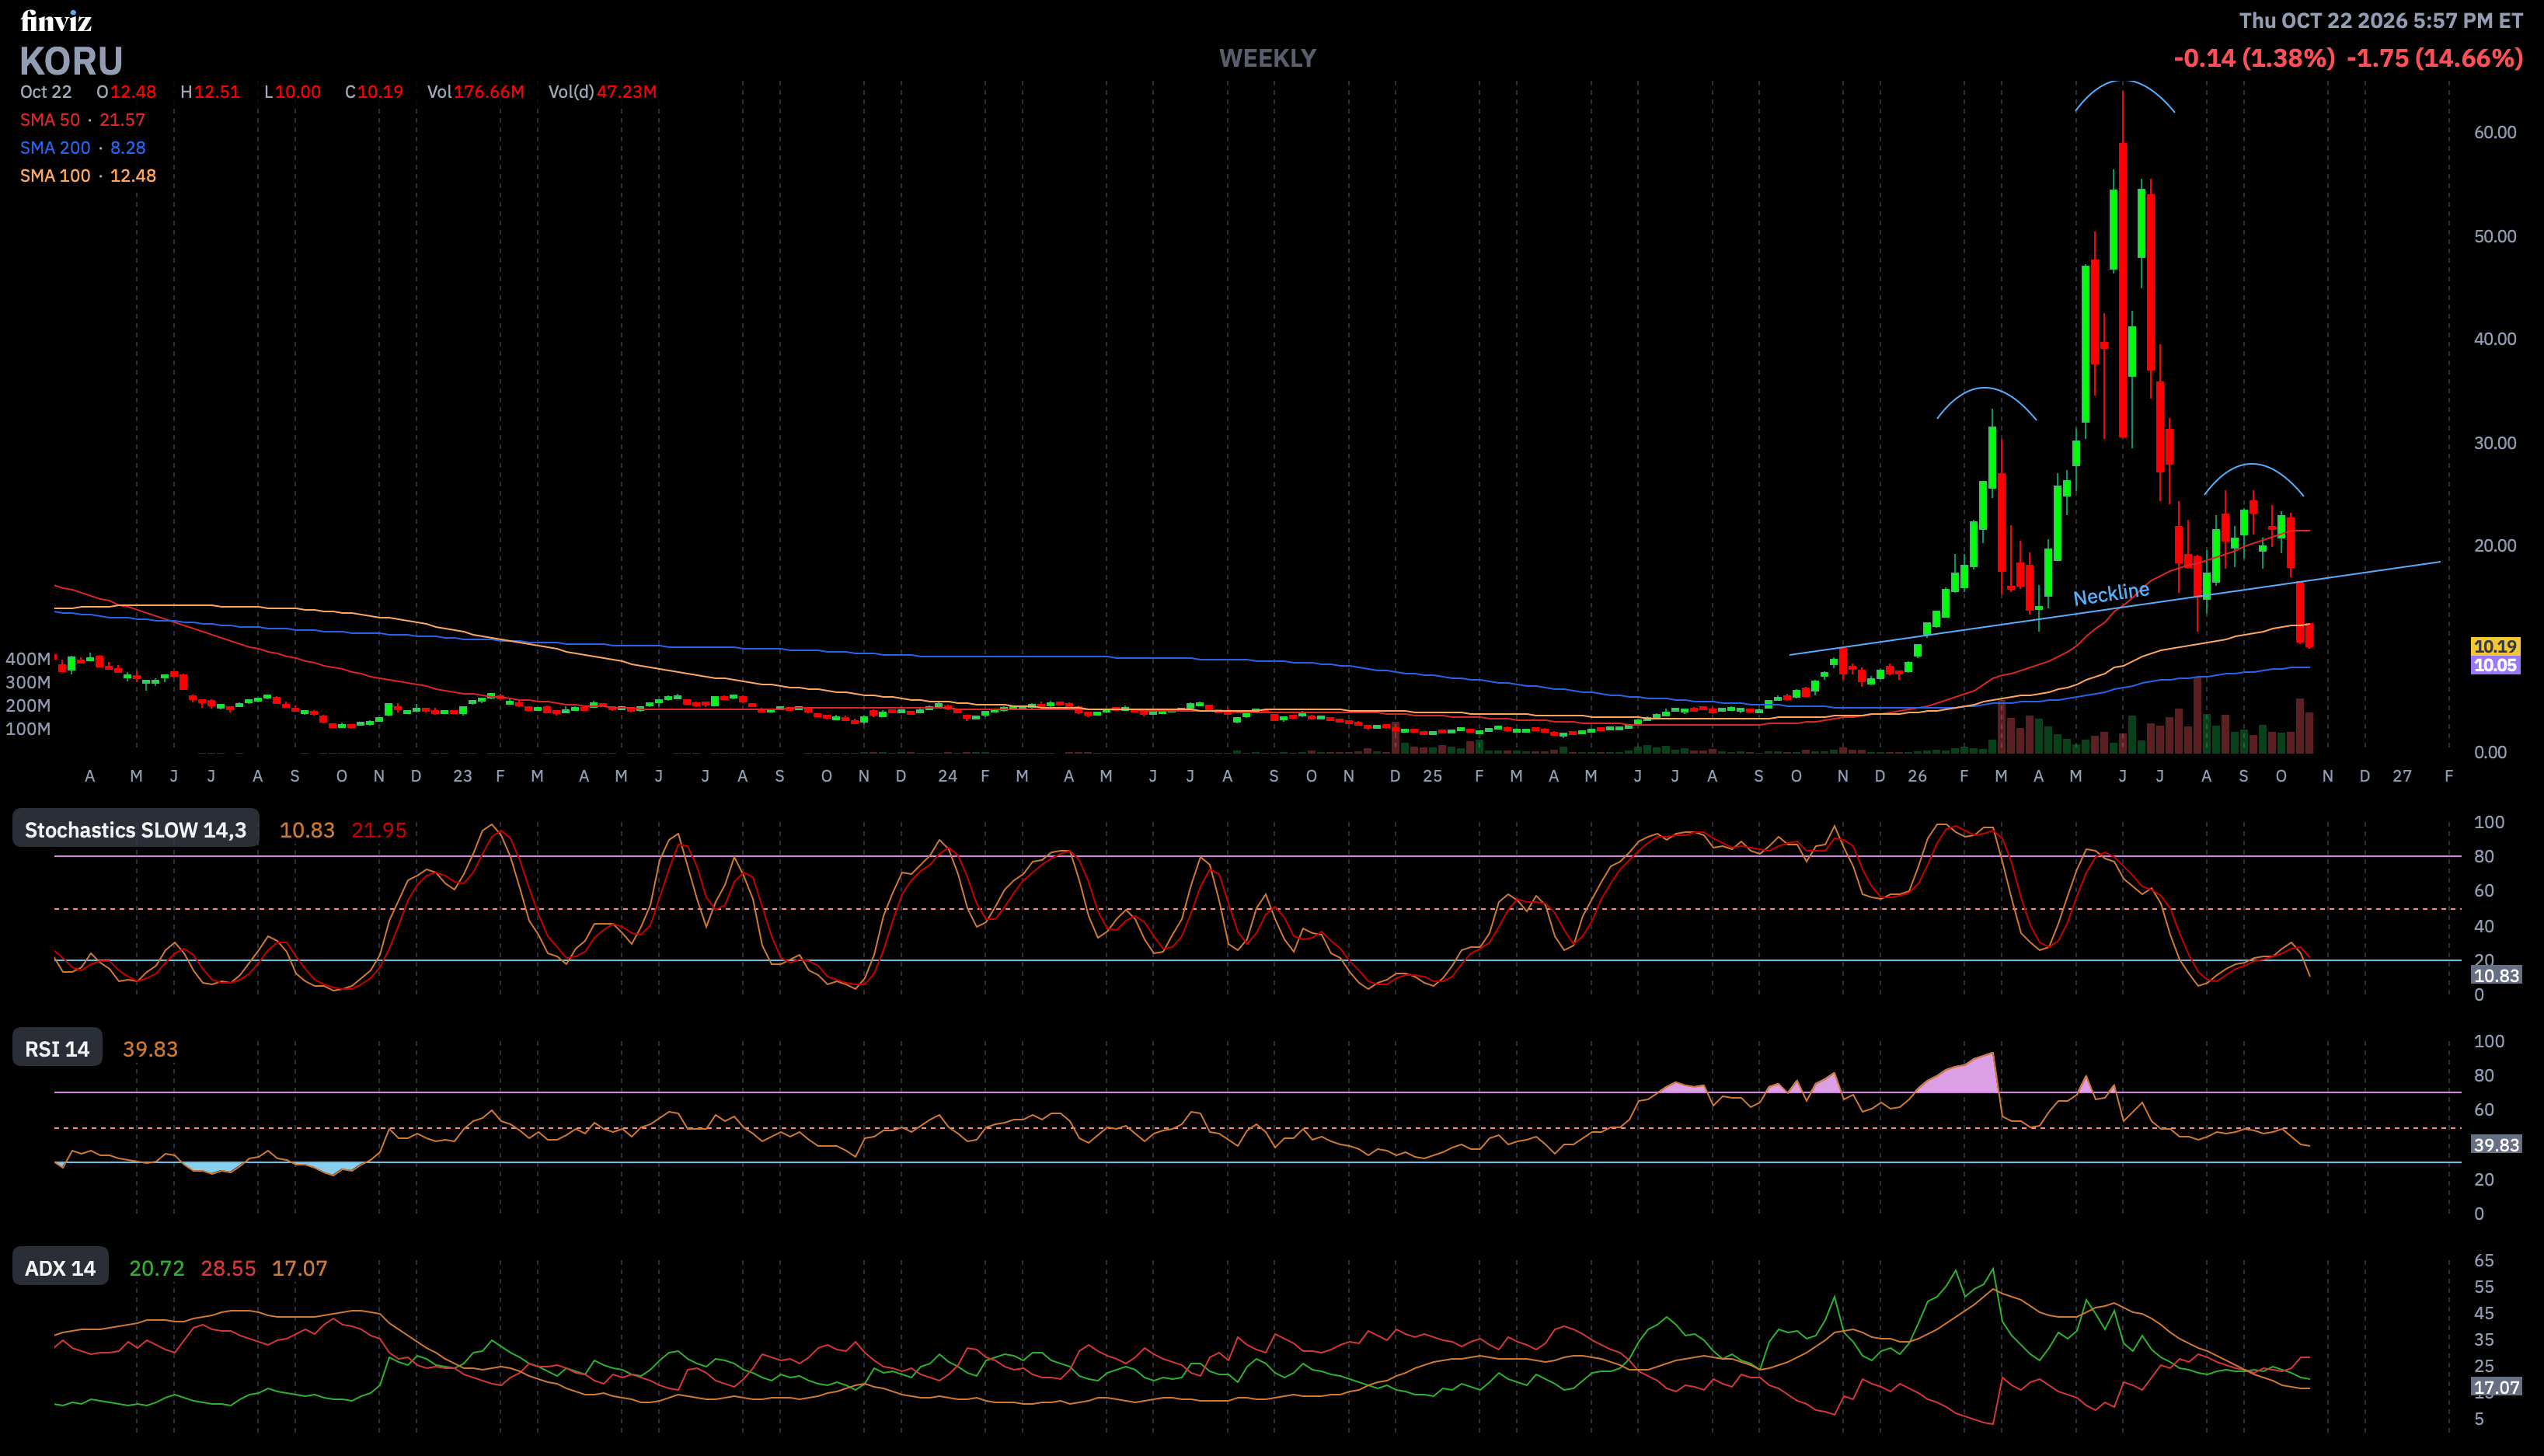
$KORU I see so many retail traders treat 3x levered funds like standard stocks.
That’s how accounts get vaporized.
Look at KORU (3X South Korea bull).
• 52-wk high: $63.99
• Current print: $10.19
• Drawdown: -84.08%
And the wild part? Even after an 84% collapse, this thing is STILL up +62% off its 52-wk low ($6.28).
For anyone buying the dip or holding bags thinking it'll just bounce back to erase those massive losses, the math doesn't work that way.
• A 50% drop takes a 100% rip just to break even.
• An 84% plunge requires a +528% gain just to reclaim old highs.
Factor in daily reset compounding and volatility drag (beta slippage), and holding a 3x instrument through chop or trend reversal is financial self-immolation.
These are tactical intraday/swing rentals. NOT marriage material. Stay safe out there y'all and GL.
$NIKE Barclays lifting Nike PT to $45 (from $37) with an Overweight tag post-management sit-downs.
Believes shares are "near bottom" but expects a consolidation channel to digest until clear growth visibility returns. Achievable FY27 numbers take the immediate tail-risk off the table, even if FY28 estimates face a trimming.
Desks now stepping up to call the floor, but waiting on the growth turn. Classic bottoming sequence, IMO... support holds first, multiples expand second, revisions follow. Let the base form and watch the range boundaries.

Credit where credit is due... hats off to the team at @finviz_com
The platform continues to make massive strides, but the new Dilution tab is a genuine home run.
Having immediate, native access to:
• Risk scoring (Dilution, Offering, Cash Need, Overhang)
• Cash runway & burn trajectories mapped against reported cash
• Granular breakdown of ATM capacity, convertible notes, warrants, and shelf registrations
No more jumping across tabs or external tools just to evaluate capital structure and financing risk during single-stock DD. It’s all consolidated right on the ticker dashboard.
Phenomenal execution and UI layout. 👏


$SPCX JPMorgan just doubled their PT on SpaceX to $500 (from $240), maintaining Overweight.
Key takeaways from Doug Anmuth’s note:
• Beat on sales across all three operating segments
• The primary growth engine shifting to super intelligence
• Compute scaling: 2–3 GW by year-end 2026, adding another 10 GW in 2027 (crushing prior expectations)
• Management also confirmed no equity raises on the table
Been long since my orig $135 IPO allocation and aggressively bought the post-IPO dips. Core position has now officially doubled.


$EYPT New starter long in EYPT, a company now trading at a third of its cash after Monday’s 85% wipeout.
Quick context for anyone new to the name: EyePoint ran two identical Phase 3s of DURAVYU, a 6 month TKI insert, in wet AMD. LUGANO missed non-inferiority in Aug and took the stock from the mid-teens to the mid-single digits. Monday, LUCIA missed the same primary EP and the stock closed down 85%, $2.99 to $0.44. Same morning, EyePoint announced a 53% workforce cut and an early end to the wet AMD trials to prioritize the DME program, which reads out in Q4 2027.
I picked up a starter around $0.41.
The math:
• ~$118M cash and short-term investments at 9/30 (company estimate, 8-K filed Monday)
• ~88.8M economic shares (86.2M common plus 2.6M pre-funded warrants)
• ~$1.33 cash per share vs. a $0.45 stock. The market is valuing the company at about a third of its cash
• Negative EV of roughly $78M. No funded debt; the ~$22M liability is leases
• 12M options outstanding at a $12.75 weighted-avg strike. No comp-plan overhang
Why I think it's overdone:
• Monday traded ~184M shares, more than twice the share count. Looks like specialist money liquidating, not price discovery
• The drug did something. 38% reduction in treatment burden, 52% of eyes supplement-free through week 56, clean safety with redosing. It missed a vision non-inferiority bar. It did not throw a safety signal
• DME is a different disease, with an inflammatory component vorolanib also hits through IL-6/JAK1. Phase 2 VERONA showed +7.1 letters and 73% supplement-free vs. 50% for control at week 24
• Both DME Phase 3s are fully enrolled at 551 patients. The hard part is done, and at this price the market is pricing that readout at zero
• The cost cut had to happen, and they did it the same day
Tell of the tape: RSI is 15 on the daily, 23 on the weekly and about 10 on the 4-hour, with stochastics pinned near zero on all three. That’s a capitulation profile across timeframes. The 50-day at $4.68 doesn’t matter for now. This trades off Monday’s range.
Levels I'm watching:
• $0.40 -- Monday's low and the 52-wk low. My line for the starter
• $0.475 -- today's high
• $0.55–$0.60 -- Monday's open and high. A reclaim puts the gap-day shorts offside
• $1.00 -- Jefferies' and RBC's new targets, and the Nasdaq listing line
Sizing: The cash pile isn’t static. Q3 burned roughly $75M, and Monday’s release dropped the runway guidance that ran in every prior quarter. The Q3 report should show how far $118M stretches and whether a raise comes before the DME data. That’s why this is a starter. I’ll add on strength or on a better-than-feared burn number. If the fundamentals change, I’m out.
Bottom line: a third of cash after a binary miss, a fully enrolled Phase 3 in a better-suited indication, and a 53% headcount cut announced day one. The pendulum swung all the way. I’ll take the cheap option.
Just sharing my work. Check everything yourself. Not financial advice.

$AIXI refuses to stay down... nine lives on this bugger. Every time the market writes the obituary, it shakes off the flush and fights back to $3.00+. With this structure, honestly, nothing would surprise me... a complete breakdown or a vertical squeeze to $40 would both fit right into the script. 🚀
$MOS stepping in and backing up the truck right here.
Mosaic has been in full liquidation. After tagging the $26 handle on Sep 9 ($26.96), it has been absolutely pummeled, straight down to the $17 handle. That’s a 34% drawdown in six weeks, capped by yesterday’s 12.5M-share flush and a fresh low this morning at $17.83.
The bal sheet tells a completely different story, IMO. Book value is $36.06 per share as of the Jun Q, and tangible book is $33.01. At $17.86 you’re paying roughly 0.50x book and 0.54x tangible for one of the largest phosphate and potash franchises in the world.
The market is pricing Mosaic as if the margin trough is permanent. Fertilizer is a cycle, not a funeral.
Sellers have pressed this thing into ER on Nov 3, and the $0.88 divi now yields 4.9%. For anyone with a multi-month/year horizon, buying hard ag assets at half of equity is the kind of dislocation you wait years for.
Just my two cents. NFA

PR out this morning on $VTGN: partnering with GATC Health to apply predictive AI modeling to their lead clinical pipeline.
The focus is derisking protocol development for fasedienol’s upcoming Phase 3 SAD study (LSAS endpoint) and their Phase 2 depression/menopause programs.
Coming right off multi-month support at $0.20, this is setting up nicely, IMO, as management pushes the clinical pipeline forward. Sitting on 50k shares at $0.21... watching for volume to start picking up.


$ACH Quick backstory for anyone not tracking this one. Accendra is the old Owens & Minor, now a pure-play home-based care business (Apria, Byram) after selling the products segment at the end of 2025. In Aug, a Q2 miss, a guidance reset and a CEO retirement announcement gapped the stock from roughly $3 to under $1.50. It has bled nearly every session since and closed today at $0.22.
That said, I initiated a 20K share starter at $0.21.
Tell of the tape... technicals I'm looking at
• Daily RSI 11.20. Slow Stochastics 3.10 / 3.41. About as stretched as a daily chart gets.
• ADX 66 with -DI at 45 and +DI at 4. This has been a one-way trend, not a choppy one. The tell I want is ADX rolling over.
• 4.78M shares traded today, roughly 3x the average. Capitulation volume tends to look like this.
Why there's a trade here, IMO
• Market cap is about $17M against roughly $1.71B of net debt. The equity is a ~1% sliver of enterprise value, so small changes in how the market values the business move the stock in multiples.
• No near-term maturity wall. The Jun debt exchange pushed the secured notes out to 2032 and 2033.
• $300M revolver was undrawn at quarter-end, with ~$271M available after letters of credit.
• Management floated an ATM in Aug, then pulled it.
• BofA's latest 13G shows 8.27M shares, 10.8% of the class as of 9/30, up from 3.78M at the end of Q2.
• Street targets run $1.30 to $1.75. They're stale, but every one sits above the $1.00 handle.
Levels I'm watching
• $0.88: the 50-day SMA and the Sept breakdown shelf. A clean 4x from here. The 50-day is falling fast, so a first test likely comes in lower. I'll take it.
• $0.195: where market cap crosses $15M. NYSE suspends on a 30-day avg below that, with no cure period. That's the real clock on this name, IMO... more than the $1.00 notice, which carries a 6 mo cure from Oct 6.
• Q3 print: not yet confirmed, expected late Oct to early Nov.
Bottom line: Again, it's just a spec mean-reversion flyer... and sized as one. 20K shares leaves plenty of room to add on intraday flushes or confirmation of a turn, and the market-cap line above is exactly why I'm not swinging bigger out of the gate. When these washed-out, heavily traded small caps finally turn, the trip back to the 50-day doesn't take long. Anyway, stay tuned. I'll provide an update at some point.
As always, just sharing my work. Check everything yourself. Not financial advice.

$QNT Fresh PR out this morning. Quantinuum just shattered the world record in quantum error-correction on its commercial Helios system.
The raw specs:
• Achieved 99.9995% logical fidelity, translating to just 5 errors per 1 million operations.
• Error rate comes in 10x lower than their own record set last month, and 100x lower than Google Quantum AI’s published superconducting benchmark.
• Puts core accuracy metrics directly into the target zone for Apollo, their planned fault-tolerant system on track for 2029.
This validates why Morgan Stanley called them the pure-play execution leader when upgrading the stock last week. The fidelity and error-correction gap between trapped-ion and competing modalities is widening fast.


$SWMR Picked up a 1/3 position at $9.20. Downside looks completely overdone in the short term, IMO... just like a lot of names across the small-cap space right now. I'm playing this strictly for a trade and a potentially explosive snap-back move, but I've got it on a very tight leash. Giddy up!
$NMRA bouncing nicely off the lows, but it’s still ridiculously oversold. A simple reversion to the 50-day SMA puts it at $1.04. That’s not a moonshot call, it’s just a return to the mean.
$NMRA Stepped in and scooped 20k shares at $0.37 w/the stock down another 15% today.
Again... indiscriminate biotech selling handing out gifts. A simple mean-reversion bounce to late Sept is an immediate 2x, while reclaiming the $1.50 base where it traded all summer before the relentless waterfall breakdown is a 4-bagger from this entry.
Downside is heavily buffered by cash... risk/reward here is completely skewed in our favor. Sizing locked in. Letting it play out from here.