

The next decade is being built right now. We find the winners early: the money, the tech and the people behind it. https://xitter.cf/t.co/KsXHkSm0Z3
Joined March 2021
- Tweets820
- Following85
- Followers57
- Likes470



Pinned Tweet
$100T BY THE END OF 2036?
For $SPCX, that’s an extreme bull-case thought experiment—not my base case. But it forces a much more interesting question than “how many rockets can SpaceX launch?”
What businesses could it build if access to orbit became dramatically cheaper?
My thesis starts with Starlink. SpaceX can launch infrastructure it owns, then sell the service repeatedly. The launch isn’t the end of the transaction. It’s the beginning of a customer relationship.
Starship could expand that opportunity. If frequent, fully reusable operations deliver the intended economics, larger payloads could enable more capable satellites and services that are impractical today.
That’s what makes me bullish: not launch revenue alone, but the possibility of owning more of the infrastructure—and the customer relationship—above Earth.
But $100T demands an entirely different scale of business. At an illustrative 50× earnings, it implies $2T in annual profit. Cheaper launches and satellite subscriptions alone are not a sufficient argument. Entirely new, enormous profit pools would have to emerge.
Execution, capital requirements, spectrum and competition could all break that path.
I’m bullish on the platform. The headline is a question. The business must earn the answer.
NFA.
#SpaceX #Starship
🤖 Made with AI

🛢️ OIL JUST LOST ~7% IN A DAY ON IRAN PEACE-TALK SIGNALS
Brent fell as much as 7.3% to $105.14 and WTI about 7% to $96.87 after Iran's president said the supreme leader had granted the government "certain authorities" for peace talks. A Qatar-mediated draft proposal is circulating. No deal is signed.
The cushion is thin: the world has drained nearly 1 billion barrels from inventories since Hormuz was disrupted, per ADNOC's CEO. That's roughly 10 days of global oil demand.

UPDATE: Reuters reports CENTCOM is forming "Task Force Iron Gate" to curb Iran's flows via land borders and the Caspian. CENTCOM says the naval blockade has blocked $25B+ of Iranian oil exports.
Iran's navy claims a tanker hit a mine in Hormuz; not independently confirmed. NFA.
UPDATE: Saudi Energy Ministry (SPA): "limited" shrapnel damage to an Aramco administrative building in Riyadh after an "attempted attack". No casualties.
Our read: an office, not a production site; no confirmed direct hit. Not an all-clear on output. NFA
spa.gov.sa/N2720650
Nautilus can count single protein molecules and tell their versions apart (Nature Methods, Sep 4). Now $114.3M of cash, a runway into Q1 2028 and a mid-2027 launch must prove labs will buy. The science, the cash and the 1T math: $NAUT xitter.cf/BetTheDecade/status/21…


The full 10-minute $NAUT breakdown is live. In the Nature Methods paper, 12 antibodies read single tau molecules carrying up to 6 phosphorylations each, detail bulk methods average away. Also covered: why the launch keeps slipping (pre-orders now targeted early 2027).
youtu.be/DzTumZCqJLA
NFA

Casgevy did $99.2M last quarter, ~6x a year ago. The first CRISPR medicine is ramping.
One course of CTX310: LDL-C −53% a year later. 2 FDA RMATs. AHA data Nov 9. ~47% of the market cap is cash.
Full article: xitter.cf/BetTheDecade/article/2…
$CRSP · Not financial advice.


IREN’s strongest argument is that the AI pivot is already showing up in revenue, not just in a construction plan.
In its Nov. 5 Q1 FY27 report, the company reported $200M of AI Cloud revenue out of $228M total. That changes the question: less “can a miner sell AI compute?” and more “can it bring the next contracted capacity online on time?”
My bullish case rests on that conversion. Power and GPUs become valuable together only when customers can actually use them. Commissioning turns a signed promise into a recurring service; another contract alone does not.
The company’s Nov. 5 update put its operating target for more than $4B of contracted ARR in January 2027. That is a company target, not revenue already earned.
What would weaken the thesis? More slippage without operating progress, or financing that leaves shareholders funding growth faster than they benefit from it. A funded project can still be late.
The milestone I care about is contracted capacity becoming billable capacity. If IREN delivers that, the AI business has a much stronger foundation than a miner-pivot label suggests.
$IREN — NFA.
📅 Tomorrow's market calendar: Sunday, Nov 8 (all times ET)
🇦🇺 5:30 PM: RBA Assist Gov Hunter speaks (UBS Australasia Conference)
🇨🇳 8:30 PM: China October CPI (est. 0.8% y/y, prior 0.9%) and PPI (est. 5.3% y/y, prior 5.0%)
🇺🇸 US stock markets closed
#Markets #China #Inflation
Nature Methods: 130 tau proteoform groups, read one molecule at a time — Q3 revenue ~$234k, mostly a grant.
youtube.com/shorts/Een84aODk…

🚨 $WULF Q3: HPC LEASES NOW 83% OF REVENUE
Revenue $76.2M — HPC lease $63.0M, digital assets $13.2M.
Adj. EBITDA −$12.8M. GAAP NI ~$710M = mostly non-cash warrant FV (+$728M). Diluted EPS −$0.03.
Lake Mariner: 102 MW live + 336 MW building ($8–10M/MW guide held).
Justified: Anthropic ~401 MW / ~$19B 20-yr lease + Google credit backstop (Nov 4) + Fluor EPC.
Muskie power →1 GW. Cash+restricted ~$2.4B.
AI landlord print, not a miner story. We hold $WULF. NFA.
$WULF #AI #HPC #Earnings

Q3 mix is the tell: ~$63M of HPC lease inside $76.2M total — 102 MW online, 336 MW still building at Lake Mariner.
Full breakdown: youtu.be/3mWAJlRxxF0
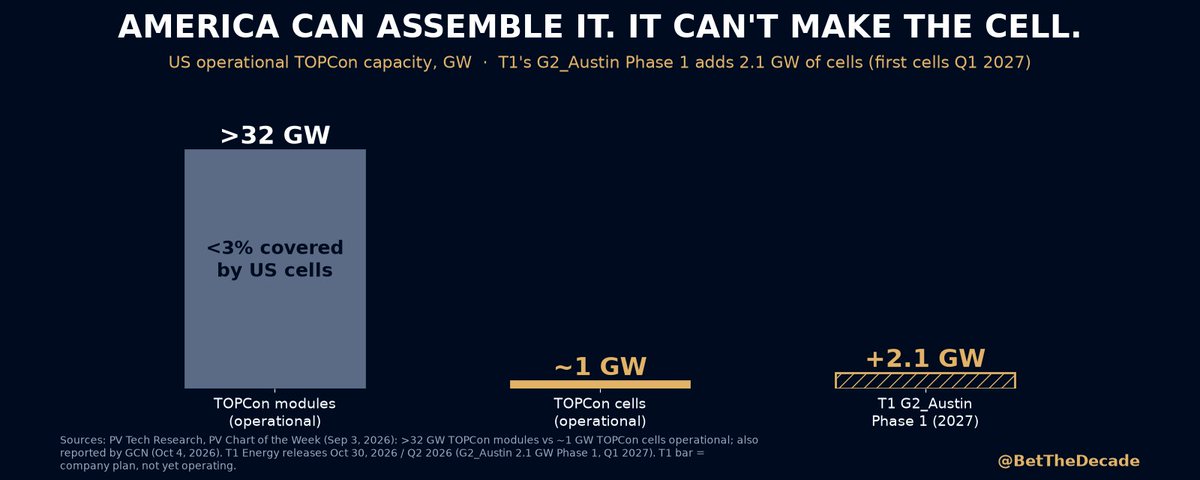
America runs >32 GW of TOPCon module lines and ~1 GW of TOPCon cells to feed them.
T1 Energy owns the TOPCon patents, a 5 GW module plant and a 2.1 GW cell fab due Q1 2027. Market cap: ~$0.7B. Q3 on Nov 12.
Full article: xitter.cf/BetTheDecade/article/2…
$TE · Not financial advice.

SpaceX’s biggest opportunity may not be winning a larger share of today’s launch market.
It may be making things economical that nobody can afford to build today.
That’s why I think looking at Starship only as a bigger rocket misses the investment thesis.
If launch becomes cheaper and more frequent, companies can design different satellites. They can replace hardware sooner. They can test ideas that would never survive the economics of an expensive, infrequent ride to orbit.
More customers could justify more flights. More flights could spread development and infrastructure costs across more missions. Lower costs could attract the next group of customers.
But that cycle has to be earned. Recovering a vehicle is not the same as turning it around cheaply. Demand is not guaranteed just because capacity exists.
Here’s what would strengthen my conviction: the same hardware flying repeatedly, less work between flights, and customers building businesses around that availability.
I’m bullish on the possibility that SpaceX expands the market rather than merely dominates it.
Not because a huge valuation is inevitable. Because changing the economics of access to orbit could change what gets built there.
Not financial advice.
ELON MUSK ON STARMIND — AI COMPUTE IN SPACE
First StarMind computers, co-designed with Nvidia: start launching ~Q3 2027, significant volume in '28, very large volume in '29.
His reason: you can't hit terawatt/year of AI on the ground — or even ~200 GW/year — because there isn't enough power. If compute follows power, the next racks leave Earth.
Source: "Elon Musk STUNS In New Interview With Predictions & Opens Up (With Timestamps)", Matt Pocius on Tesla Stock & Money, Nov 6, 2026 (Ron Baron / 33rd Annual Baron Investment Conference). Clip from 33:28: youtube.com/watch?v=IjWbvz95…
IonQ Q3: revenue $173.8M (+336% YoY), backlog $1.2B, FY guide up to $505–515M.
The edge no one else in quantum has: it owns the trusted US fab its rivals use, and management says 2027 Superion 256 capacity is sold out.
Full article: xitter.cf/BetTheDecade/article/2…
$IONQ · Not financial advice.


GOOGLE EXEC RESIGNS FROM SPACEX BOARD
Donald Harrison (Google Global Partnerships president) left SpaceX’s board effective Nov 4. Nov 6 8-K Item 5.02: not due to any disagreement on operations, policies or practices.
10+ years on the board (joined ~2015 with Google’s investment). Alphabet still largest institutional holder; Google stake ~555M shares (up from 551.2M) — not an exit. Google: still “deeply supportive.”
Board seat ≠ shareholder exit. NFA.
$SPCX #SpaceX #AI
