

"Project Easter" was a fraud. Round-tripping, Manolete & Malta. “Project Picasso” also a fraud.
Joined March 2025
- Tweets2.8K
- Following569
- Followers473
- Likes2.7K



Pinned Tweet
This is how Aldag operates. Pretend tenant is fine. Behind scenes extreme distress and inability to afford rent. $MPT finds way to recap tenant without changing rent. Tenant sends cash back for “rent.” Aldag touts tenant “current” on rent and everything fine! It’s the playbook.

Get a load of the deterioration in touts. $MPT
Yes, there is indeed round-tripping. It's "at the very heart" of the fraudulent model.
It continues to this today on largely the same collection of assets.


Yes, the equity was always a zero. Yes, it was indeed “game over.” And yes, $MPT was always a fraud.
5
17
1,662
AMARAL Capital retweeted
This is how Aldag operates. Pretend tenant is fine. Behind scenes extreme distress and inability to afford rent. $MPT finds way to recap tenant without changing rent. Tenant sends cash back for “rent.” Aldag touts tenant “current” on rent and everything fine! It’s the playbook.
Get a load of the deterioration in touts. $MPT
Yes, there is indeed round-tripping. It's "at the very heart" of the fraudulent model.
It continues to this today on largely the same collection of assets.
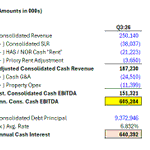
This is actually one of the easiest $MPT quarters to analyze. Keep it simple. Can be told in one graphic:
MPT generates ~$605 million of consolidated annual cash EBITDA with no growth, adjusting for:
- HSA / NOR rent that is round-tripped by MPT, and
- The 18% Priory cash rent cut.
Compare this to now contractual annual cash interest of ~$640 million!
MPT does not generate sufficient cash flow to cover its consolidated debt service. And this is before add'l tenant loans and "capex."
$MPT is now borrowing to service its existing debt = ☠️.

AMARAL Capital retweeted
Why hasn’t $MPT disclosed the $INFRAC shareholder agreement limiting timing and amounts able to be sold, and therefore $MPT liquidity from the stake?
Seems material? Do the secured bondholders know?
Ask $MPT management about the shareholder agreement, whereby they have agreed to retain at least ~25% of Infracore one year out, ~20% two years out, ~15% three years out, and ~10% four years out.
So whatever this circular arrangement is worth, as they continue to "own" and "invest" in the money-losing SMN opco tenant, they can't monetize it all even after the 180 days.
Let management deny it. That way they can add to the ever-growing pile of fraudulent statements they have made.
So how can that be a solution to the October bond maturity? Answer: it cannot.
Why hasn’t $MPT disclosed the $INFRAC shareholder agreement limiting timing and amounts able to be sold, and therefore $MPT liquidity from the stake?
Seems material? Do the secured bondholders know?
Ask $MPT management about the shareholder agreement, whereby they have agreed to retain at least ~25% of Infracore one year out, ~20% two years out, ~15% three years out, and ~10% four years out.
So whatever this circular arrangement is worth, as they continue to "own" and "invest" in the money-losing SMN opco tenant, they can't monetize it all even after the 180 days.
Let management deny it. That way they can add to the ever-growing pile of fraudulent statements they have made.
So how can that be a solution to the October bond maturity? Answer: it cannot.
AMARAL Capital retweeted
Put the dividend on the side for a second. $MPT
Sitting here today $MPT is actually (not effectively) borrowing to service its consolidated debt. Consolidated cash flow is below all consolidated cash interest cost = game over. Consolidated cash flow is largely contractual.
Forget covering the dividend. There’s no value below the debt.
Put the dividend on the side for a second. $MPT
Sitting here today $MPT is actually (not effectively) borrowing to service its consolidated debt. Consolidated cash flow is below all consolidated cash interest cost = game over. Consolidated cash flow is largely contractual.
Forget covering the dividend. There’s no value below the debt.
AMARAL Capital retweeted
Get a load of the deterioration in touts. $MPT
Yes, there is indeed round-tripping. It's "at the very heart" of the fraudulent model.
It continues to this today on largely the same collection of assets.
So interesting to see $MPT move “down market” on the paid touts.
Can barely afford daily posting anymore! Quality really falling off.
Sad.
3
7
815
lol these clowns bought back ~10mm shares of stock. How do the bondholders feel about that? $MPT

4
9
2,351
AMARAL Capital retweeted

In many cases, when HSA actually shows up after exhausting delay tactics, it has refused to provide court-ordered discovery on its financial condition. Trade secret! Just like Steward & TRACO. So why is HSA unable to produce audited financial statements? Recurring theme for $MPT.


More HSA defaults in real time. $MPT

HSA bad faith evident as it defaults upon one settlement agreement after another "ghosting" counter-parties which held off on pursuing legal remedies. The AHS/HSA/NOR enterprise clearly unable to pay its debts as they become due. Never adequately capitalized. Alter ego = $MPT.


1
6
728
AMARAL Capital retweeted
Game over. You’re done. $MPT
All that’s left playing for is prison or no prison.

Game over. You’re done. $MPT
All that’s left playing for is prison or no prison.
It was, indeed, “game over.” Steward was fatal. $MPT
A real-time (Sep. 2026) look at "Nero" (Aldag) fiddling as Rome ($MPT) burns. Touting the new HQ as MPT crashes. At least ~$150 million to build! Lien'd up, and about to become recovery for the creditors?
"... growing again... ~$100 million of acquisitions in 2025..." - Aldag (!!!); roughly half was to settle the EPDA pledge, the other half was to recap existing tenants (round-trip)! Growing again?!
“This was our one big opportunity to really build something that will save the planet, if you will,” Aldag said.
A perfect caricature of $MPT, and its leader.
vestaviavoice.com/news/medic…

12
795