

NASA I DARPA | MIT AI Lab | Venture Capital | Biosecurity | Media (founded Brainworks, Infinite Entertainment, Medio Labs, MobiTV, WiseTeachers & MicroDisplay)
Walnut Creek, CA
Joined November 2008
- Tweets28K
- Following1.1K
- Followers4K
- Likes4.4K




This is true, and one of the things I love about the SF Bay Area.

San Francisco has a unique feature that no other city in the world has. And if you want to build an outlier career, this matters a lot.
And I'm not talking about the concentration of tech companies.
San Francisco is the one place in the world that you'll be taken seriously no matter who you are.
It has an unusually low barrier to being taken seriously.
In most places, if you're 20 years old, fresh out of school, and building something, people are naturally skeptical.
In SF, that person in flip-flops and a hoodie might be building the next billion-dollar AI company.
And that changes the status quo of how people treat each other.
There's a culture of radical open-mindedness toward ambition. People are more willing to take the meeting, hear the idea, make the introduction, or give someone young and unproven a shot.
You see this everywhere. Most of the power players in SF are easily accessible – they do office hours, coffee shops, speak at events, etc.
So your age, title, pedigree, and resume matter a little less. And what you're building matters a little more.
I've traveled to many startup ecosystems, and I haven't seen this norm as strongly anywhere else.
If you're young, ambitious, or trying to do something that sounds a little crazy, that's one of San Francisco's biggest advantages.

The AI building boom is moving inside the firewall.
Replit will now deploy into your own cloud, so the data never leaves home. Amjad Masad is pointing it at government, finance and healthcare.
In sensitive work, the tools have to come to the data.
What would your team build if data residency stopped being the blocker?

A lot of developers running three coding agents have quietly become the switchboard.
One agent does one thing, another does the next, and the human carries messages between them. I hate being a low-bandwidth interface between machines, but do like the idea of being able to supervise what they’re saying to each other.
Ultimately, it’s a coordination problem, not a model problem. Agents need shared memory, transparent comms, and a clear chain of command.
Who is the dispatcher on your team right now?


A lawsuit alleges ChatGPT gave a man unlicensed medical advice that led to a mental health crisis.
Whatever the court decides, the builder lesson is already clear: a general chatbot is not a clinical care product.
AI for mental health needs clinical guardrails, a safe path to a human support and honest limits from day one.
Which of those is your product missing?

ChatGPT gave a man unlicensed medical advice, leading to mental health crisis, lawsuit alleges. cbsn.ws/4dFwATB

Dr. Phillip Alvelda retweeted

>SARS-CoV-2 Spike-specific CD8+ T cells in 40% of Long COVID cases versus 16% of recovered controls
Interesting. So at least 40% of LC cases are driven by viral persistence, but a fairly high number of recovered people also have persistence, which is I think what some suspected.

Breaking: PolyBio-Supported Preprint Finds Persistently Activated Virus-Specific T cells in a Subset of People with Long COVID
👉🏻Virus-specific immune cells show signs of ongoing stimulation and impaired function in a subset of people with Long COVID, offering a potential way to guide targeted clinical trials
1/

White-Hat system defenders using models constrained by guardrails are unlikely to prevail against the unconstrained models on the Black-Hat side.


Dr. Phillip Alvelda retweeted

Meanwhile, in the UK, the number of kids with Long Covid in England & Scotland nearly DOUBLED in a year between Mar 2023 & Mar 2024, rising to over 111K.
That’s over 1K NEW cases in kids PER WEEK across the year.
That was over 2 years ago now.
And then ONS stopped tracking it.


Machine judgment just got priced like electricity.
Perplexity open-sourced two decision models, 4B and 27B parameters, at 1 to 2 cents per million tokens.
When a call costs that little, the hard part is choosing which decisions a model gets to make alone.
Which one would you hand over first?

We just open-sourced another pair of state-of-the-art Decision Models:
pplx-decider-flash-v1.2: 4B params, 1 cent per million tokens (top 4B model on HF Decision Index)
pplx-decider-v1.2: 27B params, 2 cents per million tokens (#2 on HF Decision Index overall - for now, will improve rapidly)
Both are available on the Perplexity Decisions API as well as in the form of open weights on @huggingface
Enjoy!
Dr. Phillip Alvelda retweeted

Indonesia ran out of gasoline. This is a country where 90% of the population uses scooters that sip 90mpg. They keep their domestic consumption quite low.
Economy is grinding to a stop and people cant get to work.

🚨 MASSIVE CRASH: 🇮🇩 Rp 848,000,000,000,000 ($47 BILLION) wiped off Indonesia’s stock market as stocks plunge around 11.5%.
The biggest daily drop since 1998.
This is insane...

swyx's team took a $43,000-a-year SaaS they actually pay for and ran a weekend hackathon to clone it.
The death of SaaS just stopped being theoretical. The moat is no longer the code, or even the operations. It is the data and workflow, all gated by trust.
Which tool in your stack would you clone first?

🆕 How to Kill Your SaaS
youtu.be/zlD-CkLVKtU
A lot of people talk about the death of SaaS but mostly in theoretical terms. We took a real $43,000/year SaaS we use and launched a global hackathon to clone it in a weekend, with both AI and REAL HUMAN evals, using any models any harness.
72 submissions, a lot of manual evals and ~100B tokens later, here are the results
In this special @latentspacepod edition we share the data collected, what's still hard about killing nontrivial, midtier SaaS, and reveal the winners of the $10,000 Kill My SaaS contest with qualitative interviews!

Dr. Phillip Alvelda retweeted
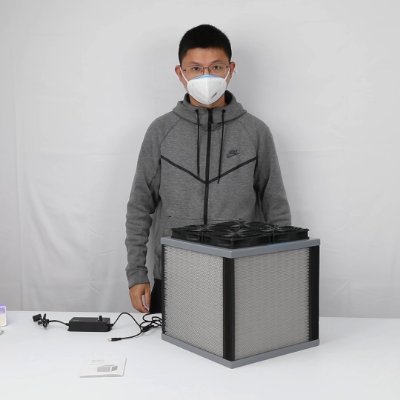
The first review of 5Pro.

My AirFanta 5Pro is here! It was a delight to order, arrived in 2 days (!), took about a minute to assemble (oh, how *easily* and satisfyingly it clicks together!) and runs like a dream.
Thanks @Engineer_Wong !

ALT Fully assembled air purifier on a grey table with dog in background

ALT Digital monitor showing fan speed and PM2.5 counter
Dr. Phillip Alvelda retweeted

Upgrading PPE for staff working on COVID-19 wards cut hospital-acquired infections dramatically
When Addenbrooke’s Hospital in Cambridge upgraded its face masks for staff working on COVID-19 wards to filtering face piece 3 (FFP3) respirators, it saw a dramatic fall – up to 100% – in hospital-acquired SARS-CoV-2 infections among these staff.

Dr. Phillip Alvelda retweeted

That toxic combination of Covid and EBV. Another athlete, another life, devastated. Not even touted as a mystery this time. Will people try harder to reduce Covid risk because of this front page article which did actually mention Covid? bbc.co.uk/sport/athletics/ar…


This seems a little more positive, and probably well-received by the frontier labs.
Thoughts?

Anthropic just reported $16.8B of revenue in a single quarter. Two quarters ago it was $4.7B.
That one number answers the question the whole market is panicking about this week. Here's the math, step by step.
1. The fear
Big Tech is on track to spend ~$1.2T on AI infrastructure next year. More and more of it is borrowed. The bear case is simple: trillions go into chips, buildings and power, and the revenue never shows up. That's why AI infrastructure stocks just got crushed.
2. The only question that matters
How much revenue does one unit of compute produce?
The unit is the gigawatt. One GW of AI compute is a campus with hundreds of thousands of chips, drawing the power of roughly 800,000 homes.
Goldman Sachs did the math on everything that goes into it: chips, buildings, networking, power. For the buildout to earn a solid 15% return, each GW needs about $11.6B of revenue a year.
3. What Anthropic actually earns
Anthropic ran about 1.4 GW at the end of 2025 and plans ~5 GW by the end of 2026, so it averaged roughly 3.5 GW last quarter.
$16.8B a quarter is $67B a year. Divide by 3.5 GW and you get ~$19B per GW per year.
That's 1.6x Goldman's bar. Where the demand is real, the capex is already profitable today. Not in 2030. Today.
4. Proof the demand is real
Anthropic spent this year rationing its own customers. It cut usage limits at peak hours because it ran out of compute. Now it's buying capacity from Amazon, Google, Microsoft, SpaceX, Nscale, Lambda and IREN all at once. ASML says the machines that make the chips are sold out through 2028.
When the seller is rationing, the problem is supply.
5. The loop
Revenue buys compute.
Each new GW starts earning ~$19B a year the day it's plugged in.
That revenue buys the next GW.
That's why the debt doesn't scare me. Debt backed by $19B per GW of revenue is a business. Debt backed by hope is a bubble.
6. The line that ends the panic
For the whole industry, the buildout breaks even at ~$300B a year of AI revenue.
Anthropic alone: $67B.
OpenAI: ~$50B.
Microsoft's AI business: $37B+.
Then Google, Amazon, Meta and thousands of apps.
At this pace the sector crosses $300B in 2027. Nobody panics about borrowing to build something that already pays for itself. The financing fear dies that day.
7. What's left after that
Once money stops being the constraint, the bottleneck is physical: chips, memory, and above all power, which takes years to add to the grid.
Money is solving itself. Megawatts are not.
Bubbles burst when the revenue never comes. This one arrived early, and it's being rationed.
$BE
Dr. Phillip Alvelda retweeted
The immune system as the explanation for why the Shingles vaccine has shown protection vs dementia in 4 natural experiments
pnas.org/doi/10.1073/pnas.26…

Once the open-source models break through the more-or-less current coding performance standard set by the frontier labs, Anthropic and OpenAI will struggle to maintain both traffic and margin.
I can’t imagine this will take more than six months.
Maybe they find some cost advantages at scale, but I fear their IPO window at crazy valuations is closing rapidly.
Anyone care to bet as to ultimate valuation and timing?

This is looking pretty grim. And their early cash-out seems to indicate they saw it coming…maybe even planned for it. Starting to look like maybe a fraud investigation would be worthwhile.

Imagine an executive using the word investment grade in a conversation the same day his companies yields rise 225 bp in 2 days to 15.8% YTM
Having $13.5 billion due in principle and interest by next year on $10 billion revenue and an operating loss while all your share sale money is tied up to construction obligations.
Having no access to bond markets
Having executives/founders who sold $11 billion of stock in a year (30% of the company)
That’s $CRWV

Seems a bit of a harsh standard to say “it’s all over” for a $16B company growing 45% year on year.
Yeah, they have some debt issues, to be sure. But boy, are they having some impact while they create tremendous value.
Even if another company has to pick up the pieces after a debt restructuring, they are absolutely changing the world.
I salute their audacity and their dreams.

Dr. Phillip Alvelda retweeted

Short seller Jim Chanos - who called Enron - says AI "neo clouds" are not tech companies but equipment leasing firms - earning single-digit returns even in the boom
"Be careful that you're not putting magical valuations on mundane businesses"
He's net long AI - and still says this about the money behind it:
> The Netscape Test (0:43):
- He compared the decade before Netscape with the one after: U.S. growth was "virtually the same," and corporate profits grew 6% a year in both. His warning: don't extrapolate "much broader impacts" from AI
> The Accounting Mismatch (4:43):
- Nvidia and the data-center builders book revenue and profit "immediately." The hyperscalers spending those same dollars "are capitalizing those costs." In 1998-2000, S&P operating profits rose 30% in two years - then fell 40%
> Heroic Assumptions (6:56):
- Even with a 10-year life on the chips, "the returns on capital are going to be de minimis." Live deals pencil out at "7%, 6%, 5%, 8%" - "single digit ROICs pre-tax"
> The $2 Trillion Bet (21:21):
- On SpaceX's IPO: "the numbers don't work on the existing business," and the launch unit "still loses money." To justify almost $2 trillion, you have to "believe in Mars and the moon and data centers in space"
The AI money debate, fresh every single day

