

US Power Markets Analyst @modoenergy
New York CIty
Joined January 2012
- Tweets30
- Following72
- Followers98
- Likes43




Aaron Orelowitz retweeted

Record heat in PJM sent July's TB4 spreads soaring. Real-Time spreads averaged $895/MW-day, up 161% on last year and 88% above June.
Almost all of it came from three days. An extreme heat wave over July 1 to 3 carried 56% of the month's entire spread.
July 2 broke records across the board: an all-time PJM peak load, and the hottest average temperature the grid has ever recorded at 97°F. Washington DC hit 102°F, breaking a mark that had stood since 1872. That single day carried a quarter of the month's spread, worth 14 ordinary trading days.
Full breakdown on the Modo terminal, link in the comments below.

Aaron Orelowitz retweeted
Four states are driving PJM's storage buildout, each use a different model:
NJ: fixed incentive, developers keep market upside
MD: hedges capacity revenue
IL: hedges the entire revenue stack
VA: utility mandate, mostly Dominion
Full breakdown: eu1.hubs.ly/H0xD9Qz0

Aaron Orelowitz retweeted
82 batteries cleared Phase 2 of PJM's Transition Cycle 2, totaling 8.5 GW of interconnection rights.
That's 28% of the active queue. Storage is now a meaningful share of what's moving through PJM's pipeline.
A few takeaways from this checkpoint in the cluster study:
1. Virginia leads by a wide margin. 33 of the 82 batteries are sited there, at 3.2 GW. Illinois is next at 1.5 GW, then Maryland at 1.3 GW.
2. Long duration is starting to show up. Nine ten-hour projects cleared, mostly solar-paired systems in the Midwest.
3. PJM's two new fast-track policies did little for storage. Transferable capacity rights went mostly to solar (14 of 18 projects), and the Reliability Resource Initiative went almost entirely to gas. Just 3 of its 41 active projects are batteries. Both were meant to speed capacity into a tight market, and both mostly favored other technologies.
4. Interconnection costs vary widely, and not with project size. They run from about $3,000/MW to $1.9M/MW, with a median near $151,000/MW. These costs will likely decide which projects drop out of the queue next.
To see the full analysis, check out the full article on the Modo Energy terminal. Link in the comments.


Aaron Orelowitz retweeted

PJM storage policy: New Jersey, Maryland, and Illinois run competitive procurements. Virginia mandates utility storage. Michigan mandates utilities only outside PJM's footprint. Pennsylvania and Delaware are forming programs. Remaining states have no policies.

ALT Chart: pjm storage policy map
PJM's capacity auction cleared at the cap again for DY 2028/29. But the uncapped numbers are even crazier: without the cap, the RTO-wide price would have cleared at $555/MW-day, with ComEd reaching $777/MW-day. There's clearly still a lot of work to do to address reliability needs in the coming years.
Full analysis: modoenergy.com/research/pjm-…

Aaron Orelowitz retweeted
If you want to stay in the loop on PJM, follow Aaron ⬇️

PJM's capacity market is in a "credibility trap." Prices high enough to spur new builds trigger interventions that cap them. The ISO's white paper offers three paths out of this trap. Which path forward do you think we'll see in the coming years?
Source: modoenergy.com/research/en/p…

PJM's capacity market is in a "credibility trap." Prices high enough to spur new builds trigger interventions that cap them. The ISO's white paper offers three paths out of this trap. Which path forward do you think we'll see in the coming years?
Source: modoenergy.com/research/en/p…
Aaron Orelowitz retweeted

also at grid scale, and in particular PJM, projected large load growth is almost entirely data centers. i'm just not sure why we're pretending otherwise. weird disconnect, as PJM is quite open about this being the major driver requiring a fundamental overhaul

Aaron Orelowitz retweeted
PJM battery revenues averaged $62/kW-month in Q1 2026, triple the pre-redesign rate. The October 2025 regulation market overhaul unified Reg A and Reg D into a single ancillary service. Regulation now accounts for $56/kW-month of the revenue stack.

ALT Chart: BGE Real-Time TB4 spreads doubled year-over-year to $658/MW-day in April, leading PJM's Mid-Atlantic
Aaron Orelowitz retweeted

I moderated a roundtable earlier this week at a storage conference on energy storage + load growth in PJM.
The main Q: CAISO & ERCOT have ~10,000 MW+ of storage each. PJM has <500 MW. Wtf??!!
Several developers & investors raised great points worth sharing.
1- Renewables penetration
- This is an obvious one, wind + solar is not huge in PJM unlike ERCOT or CAISO creating less volatility. PJM States import a lot of RECs from MISO
- But hey, SPP has HUGE amounts of wind, LOT of negative pricing, and less batteries than PJM!! Clearly RE penetration is not the only reason and anyway this will change with lot of solar coming online
2- ELCC risk
- With not much energy arbitrage, capacity market is important for revenues. But storage accreditation is variable and projections are heading down. For 4-hr, from ~60% ELCC today to just 25%(!!) in 2032. Investors are obviously wary
- One solution: allow storage & large loads to contract resource adequacy risk bilaterally, or BIGPAL. Load flexes if storage runs out. No impact on the rest of the market, maximum contractual flexibility & innovation
- Another one that came up A LOT: LDES. Short duration ELCC risk is driving lot of interest in long duration storage (12hr+) that would get ~100% ELCC. I was surprised to see so many developers mention LDES. Keep an eye on this one, particularly with LDES mandates also under discussion in several PJM States.
3- Storage bidding in the energy market
- B/c of the market monitor’s focus on market power mitigation, batteries cannot bid their opportunity cost in PJM. They can only bid their charging cost. This is crazy and needs to change
- Thankfully, PJM has recognized this and is undertaking a stakeholder process to allow short duration resources to bid their opportunity cost. Freedom & markets! 🇺🇸
4- Surplus IX Service
- Can wind/solar developers use their surplus IX capacity to add batteries? A developer pointed out this is completely unusable for wind. Because the capacity injection rights are SO LOW compared to wind ELCC, adding storage has no RA value.
- It’s the opposite for solar though, expect to see more movement there
5- Future outlook: A LOT of storage is coming on
- 2,300 MW was approved in the RRI expedited queue
- 6,400 MW already has an IX agreement across Fast Lane + TC1 queue as per great data from Modo Energy
- Load growth, IX queue reforms, as well as mandates from MD, NJ, VA are going to keep pushing this
- Co-location docket will also create opportunities for storage to directly site with large loads, if PJM can expand some of the configuration options


NY's demand growth components tell a clear story: a fundamentally transformed grid is coming. Steeper ramps, longer overnight stress, and winter overtaking summer as peak season by 2039.
Source: modoenergy.com/research/en/n…

PJM's latest capacity auction hit the $333/MW-day price cap and cleared 6.6 GW short of its reliability target. 8 proposals are now on the table to close the gap for future auctions. Excited to see how results shift in June 2026...
Source: modoenergy.com/research/en/p…

Aaron Orelowitz retweeted
We just launched early access to the Modo Energy AI Analyst in beta!
The only AI built specifically for power market insights.
The energy transition moves fast.
The teams making investment decisions need answers that keep pace.
AI Analyst draws on our complete global research library and proprietary datasets to answer your questions - with citations, in seconds.
Think of it as having direct access to our team of experts 24/7/365.
This is just the start. Tell us what works and what could be better. We’ll keep shipping so you can build the new energy system, faster.
Start using AI Analyst for free today!
Aaron Orelowitz retweeted

Fuel costs, not renewables, still set the tone for energy prices in PJM.
November 2025 shows why. A thermal-heavy stack means gas often sits on the margin, so swings in fuel prices translate almost directly into swings in power prices.
Layer in a 6% YoY load increase and higher-cost units cleared more frequently.
When gas is on the margin, even a $1/MMBtu move can mean ~$7–10/MWh in energy prices.


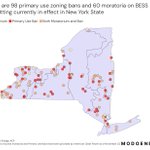
108 New York jurisdictions have moratoria and/or bans on grid-scale BESS, covering ~4,500 mi². That’s a serious roadblock to New York’s decarbonization goals...
Full analysis: modoenergy.com/research/en/n…

Interesting how some of the new batteries joining @pjminterconnect will have outsized interconnection costs, but aren't sited at nodes with higher arbitrage potential. I'm curious how they’ll make the math work…
Source: modoenergy.com/research/en/p…

New York's grid-scale energy storage solicitation has ~19 GW of eligible projects to choose from and only ~1 GW of Storage Credits to award. The Strike Prices these projects submit will be make-or-break.
At @ModoEnergy we've laid out how developers will be thinking about their submissions and where we expect bids to land.
Source: modoenergy.com/research/nyis…

Aaron Orelowitz retweeted

Developers of BESS in and out of NYC are expected to bid their ISC strike prices within a relatively tight range.
However, the subtle differences between those bids - and the resulting expectation in payout from the ISC, depending on the node's revenue expectations, are going to make all the difference in which projects receive awards and which projects do not.
Read more in our latest on the ISC solicitation here: modoenergy.com/research/nyis…
