
Real Estate developer who specializes in retail ground-up / value-add. Average unlevered IRR (no debt) of ~40%. Just sharing my thoughts and experiences.
Joined December 2022
- Tweets5.9K
- Following137
- Followers8.5K
- Likes6.5K





This is brilliance on display.


Negotiation strategy is a fun topic.
When leverage is arms-length, and interest is mutual, the vast majority of negotiations follow a very similar pattern:
- Initial LOI pushes for a wide array of unnecessary chips, which can be traded away later
- Follow a 'tit-for-tat' approach, in which each side wears out the other on what they want
- Eventually, an 'equilibrium' is found, and if that middle-point is within a tolerance zone for both sides, then a deal will effectuate
The alternative approach is a clean cut initial offer, which has extremely limited tolerance for movement.
Both tactics are effective, but the former is more common in lease negotiations, and the latter is more common in sales transactions.
Where negotiations can become very interesting is when leverage is lopsided.
This is where you hear the most entertaining stories of how a particular strategy was pulled off.
The most common?
Negotiating a price the Seller desperately wants, dragging out the LOI/PSA process, dragging out the escrow process, then slamming the Seller with a massive price reduction at the last second.
If a Seller is in financial distress and has limited/zero alternative options, they may be forced to accept. This happens more than you may think.
My favorite one?
This only works under very niche circumstances:
- Leverage is entirely sided towards one party
- The counterparty is highly logical, and driven by the numbers, and will agree to a lesser deal than they want if they still benefit somehow
- The counterparty has to transact with you, and no one else (e.g. Landlord-Tenant relationship, in which the lease is terminating on a high performing store with no extension options left, and no immediate relocation options available)
I've found that sometimes, when all these stars align, it's best for your counterparty to simply think you're crazy.
Like actually batshit insane.
I had a blend & extend deal which followed the parameters above.
I penciled the pro-forma rent at $180k-$200k/year.
Decided to interview a few brokers, and get input on valuations:
- Broker #1: $180k
- Broker #2: $150k
- Broker #3: $400k
I knew Broker #3 was completely off with his number. I did not care that he was wrong - I pushed him hard just to see how entrenched he was that he's right.
He was completely confident in it, and did not bend an inch on his assessment. So confident, in fact, that he gaslit me into (briefly) second guessing myself 😂
Structured a commission agreement in which he's paid 3x if he signs a lease with a new tenant - in effect, making him indifferent to killing a transaction with my existing tenant.
(This is an extremely high risk maneuver that I would not recommend, but I only did so because I knew how lopsided the leverage was in this particular situation. A key element was I maintained a backchannel with the COO in case my broker's negotiations soured, and I needed to 'clean up' his mess)
Puffed him up, then sent him into the negotiations and told him I will not accept a penny less.
Very quickly after, the deal landed at $275k/year, 3% annual bumps, and a happy Tenant.
In some situations, you need the other side to think you're absolutely nuts to maximize your position.
This is not a political post 😜
Working on a development project which has environmental contamination (former gas station site).
Not my cup of tea, but there is a long story behind this.
Engaged my environmental consultant to perform a Phase 2 investigation, and to provide a recommendation on how to handle the matter.
He does so.
His recommendation feels too 'light' 🙃
I decide it's best to get a second opinion, and hire a very well known, national company for this.
- Proposal is presented
- Contract signed
- Retainer funds wired
Off to the races.
ETA: 10 Business Days (ending last Friday).
On Thursday, I send a follow-up to check-in on the status.
"The report is under final review - we're expecting to get it to you by tomorrow"
Okay - nice 🥳
Friday rolls around - no report.
Monday rolls around - no report, but I get an email notification that I have a package being delivered by USPS.
Tuesday - nada
Today - my USPS package arrives.
I open it.
It's a gift box of fancy pecans, and a note from this environmental company about how important my relationship is to them 🤨
How much is this upcoming report going to end up costing me? 😂🤣
I love working with 'mom and pop' tenants, but they have their quirks.
One of my (more fun) projects was the conversion of an industrial building into a retail showroom - one of those rare situations where it works well.
Space leased up quickly to a notable operator, and they eventually outgrew the space.
Took it back out to market - 6,000 SF (not an easy pill for many to swallow).
LOI comes in from a local business, and terms are agreed to within days so I request financials.
TT financials finally arrive.
The annual negotiated rent is equivalent to their entire 2025 Gross Sales.
Oh boy😂🤣
Experienced such an off-putting interaction today.
We're in negotiations with an operator to lease an entire building:
- Experienced operator
- Well educated and well spoken
- Savvy and successful
LOI is mutually executed, and we're speeding through lease negotiations.
They come back with a small, but fair, set of comments, which I respond to within a few hours.
Tenant Broker wants to schedule a Teams call to speed things along.
It's a bit too soon for a Teams call at this stage of negotiations, but it's okay - I accept.
Principal #1: 3ND
Principal #2: Tenant
Landlord Rep #1
Landlord Rep #2
Tenant Rep #1
Meeting is far too stacked for something so simple, but it originated from the Tenant Broker who wanted an 'all hands' environment.
Okie dokie.
Prior to the meeting starting, I prepare my broker on the cadence I expect:
- He leads with the opening, an explanation of the lease form, etc., and opens the floor for engagement
Meeting starts.
My broker opens perfectly.
Tenant (Principal) immediately begins diving into the conversation, and is abruptly interrupted, and cut off, by their broker.
Tenant Broker takes over and starts leading on behalf of the Tenant side.
My reaction was simple: 🤨
We have some back and forth, and the Tenant (Principal) begins communicating certain concerns regarding a lease provision.
Before they can finish, my broker also interrupts.
I'll let bad behavior slide for an opposing side, but not from my team.
Cut off my broker, and ask the Tenant to finish their thoughts.
What the fuck is going on here?
Meeting continues for ~90 minutes, and we're simply getting to a point where we're rehashing old topics, so I end it, and say I'll get them my responses soon.
I've thought about this meeting several times today. It just put me off so much.
The only thing different about this operator, compared to other operators in the field, is that 'they' is a 'she'.
The good news is that it's the first time in over a decade that I've experienced this first hand (thankfully).
The bad news is that it still happened. Wild.
The best part about all this?
The Tenant (Principal) was the best champion for communicating their issues/concerns in an eloquent and effective format. Their broker simply confused the shit out of me 😂🤣
Tax-advantaged investing is phenomenal, but it comes with a doubled edged sword.
Many CRE deals are being shoved into a YE 2025 close due to cost segregation / bonus depreciation.
Why?
Time value of money.
Investors (that need to shield their incomes) save a ton in taxes today, and kick the can down the road (depreciation recapture tax).
We're selling a property to an investor that absolutely needs to close escrow by year-end. It's one of my first development projects I ever built, and it's my smallest transaction, but the savings are notable for this Buyer.
In simple terms:
- Down Payment: ~$1,680,000
- Tax Savings: ~$300,000 instantly
He's closing escrow on December 31, and will save $300k on his taxes by doing so. In other words, an 18% 1-day return.
Absolutely insane metric.
Will he owe this $300k in the future?
Yes.
If, however, he invests this $300k saved for 30 years at:
8%: He'll have $3,000,000
10%: He'll have $5,300,000
And he'll owe $300k in recapture taxes in the future (assuming he doesn't find a creative way to transfer his wealth to his kids).
Tax-advantaged strategies are extremely compelling for this reason. They make the Year 1 ROIC look incredible.
With that said, it also comes with a double edged sword.
I've seen too many investors gloss over glaring asset-related issues that may become a major problem tomorrow (permanent losses), in exchange for saving some tax money today.
CRE car wash investments come front-and-center to my mind.
Never let a tax-related factor drive your investment decision - whether it's to buy or to sell.
This applies to real estate, stocks, etc.
Any tax-related factor should be a secondary consequence, and should only be treated as 'icing on the cake'. It's a bonus, and nothing more.
Want a great tip?
When you have no leverage heading into a one-sided negotiation, then you need to create it.
This one is a longer story so buckle up.
- Purchased a commercial lot from a municipality
- One of the best intersections in the entire county
- Phenomenal price, but it came with hair on it
What's the hair?
A clawback right - if the lot is not developed within a certain (short) period of time, then the City can rescind the transaction.
Clawback is recorded against title, which permanently impairs the land value until it is developed.
The PSA was extremely one-sided:
- As-is
- Where-is
- Bla bla bla
However, certain Seller representations and warranties were made in the agreement.
No Seller disclosures were made during escrow.
*******************************
Time for a teaching moment:
No property can truly be sold as-is, where-is, without proper disclosures.
A Buyer can not waive away their disclosure rights (at least in California), even if they sign a document waiving those rights.
By law, Sellers need to disclose any, and all, facts that could negatively affect a property's value (desirability).
Remember to always disclose, and over-disclose, in writing.
*******************************
I engage an environmental consultant to perform a Phase 1, and it comes back fine.
We close escrow, work on entitlements/permits with our tenant-in-tow, and tenant requests an updated Phase 1 prior to lease execution.
We do so.
City provides new records to the environmental consultant this time.
Get a call from him:
- Consultant: Hey - we have a problem
- 3ND: What do you mean we have a problem?
- Consultant: Property used to be a gas station in the past. City provided new records when we made the updated request for documents.
- 3ND: 🤡
Okay.
Well.
Fuck.
Seller (City) never disclosed this during escrow.
Consultant suggests we don't need to do a Phase 2 due to how long ago the underground tanks were removed.
Fuck that.
If there's a problem, then I need to know there's a problem.
Morally - I don't want to create a cancer risk for customers in my developments.
Financially - my liability is in the millions if we find out about contamination after the project is built (remediation costs, tenant buildout reimbursement language in the lease, etc.).
Perform the Phase 2.
Report comes back.
The property is dirty.
Share the news with the Tenant, which is followed by 6+ months of lease renegotiations, and subsequent termination of the deal.
All righty then. Engage my attorneys, and we have a real claim against the City (non-disclosure).
Quite frankly, the claim can be fairly substantial.
This is, however, a City I have worked with for nearly a decade, which has many City-owned properties coming down the pipeline.
I'm not super inclined to actually skullfuck them.
So what are my options?
1) Rescind the contract and get 100% of my money back + consequential damages (e.g. soft costs like architect, engineering, attorney fees, etc.).
- Qualitative factors: City counterparts will understand, and zero reputational impact.
- Net gain: Zero
- Downside: Minimal / zero
2) Sue for negligent misrepresentation, breach of contract, fraud, etc.. Payoff will be substantially larger, but will entail 3-4 years of litigation.
- Qualitative factors: Some city counterparts will understand, however, 100% of them will be pissed and may pick other developers to buy city-owned property in the future
- Net gain: 7-figures
- Downside: Very, very hissy pissy City 😂
3) Remove the clawback right from Title.
- Qualitative factors: Depending on the approach, I can either be a 'hero' with the City or a villain. Tact will dictate this outcome.
- Net gain: ~$1M+
- Downside: Depends on how I proceed with this approach
In Development, there are only so many relationship bridges you can burn. The Developer, Tenant, Brokerage, and City communities are actually quite small, and people talk.
This is also a unique City, in which there is extremely limited turnover within their personnel, and 'institutional memory' is retained long-term.
Be careful trading short-term gains for long-term losses.
Decide to lean into attempting Option #3 first.
Let me share something with you:
In this type of circumstance, you never want to make the request (remove clawback), get rejected, then request it again after escalating the situation.
Your position will become substantially weakened, and you will be seen as a pariah.
So we need to create leverage first, and I'm willing to negotiate.
So what are we to do?
Easy.
Engaged 2 sets of attorneys to move forward:
- The 'good cop' (my sweet, older attorney who only specializes in 'peaceful' transactions)
- The 'bad cop' (my bulldog litigation attorney who will literally eat you alive)
- Engaged my litigation attorneys to file a claim against the City.
- Sent the scariest fucking letter you could imagine.
- Caught the City's attention.
This claim is not a lawsuit, but it reserves my rights to sue. It's pre-litigation, which has all the bark without the bite.
Engaged my transaction attorney to reach out to the City about removing the clawback language.
Transaction attorney schedules a call with the City Attorney and, lo and behold, the City brought their (newly engaged) litigation attorney on the call too.
City's litigation attorney proceeds to make every threat you can imagine (some of which may actually strengthen my lawsuit, if I decide to go down that road).
My transaction attorney immediately calls me, and he's obviously shaken up. He's naturally a nervous nelly, and was particularly stressed after this call.
City Attorney schedules a follow-up call with my attorney (3 days later).
This is perfect.
City is in full panic mode, and the intensity of their litigation attorney's behavior further validates this.
It's time to make a deal.
Instruct my attorney to immediately cancel the scheduled follow-up call with no explanation.
City's litigation attorney responds:
- If your client is willing to drop their claim, then maybe we can remove this clawback from Title
We now have the City originating the request instead of it coming from me. Shifts the power dynamics tremendously.
At this stage, I will get what I want:
- Removal of the clawback in exchange for dropping the claim
- City-Developer relationship remains strong
It's not enough.
I want to milk this for every ounce of benefit.
My eyes are on the incredible City-owned property coming down the pipeline very soon.
Will likely schedule an 'all hands' in-person meeting to seek resolution on this.
What do I know if I make this request?
The City will bring their executive leadership team into the meeting (some of which are also on the voting panel for selecting Developer proposals on their land for sale).
Let's just say we're going to lean heavily into a few themes:
- City has caused egregious, irreversible harm 💀
- We have a long-standing relationship with this City, and do not want to litigate (if it can be avoided)
- We're here to make a deal on this issue, and want the City to remember we let them off the hook on a 7-figure litigation
- Think about what type of Development partners you want in the future for City-owned property (the type that work together when shit hits the fan, or the type that sue)
Give me lemons, and I'll make you the best lemonade you've ever had.
Want a great tip?
The next 2 weeks are the best weeks in the entire year to negotiate new service contracts.
Not only are we at the end of Q4, but we're also at year-end.
There are many salespeople who:
1) Have not hit their quotas for Q4, year-end, or both.
2) Have (mostly) written off landing any sales over the next 2 weeks.
For data providers, the incremental revenue dollars drop almost entirely to the bottom line. This is the best time to negotiate major discounts for 1 year service contracts.
Good luck, and have fun.
Starbucks blew out of my development deal recently.
Been engaged with a few tenants, but the rent is expensive and I want the right fit.
- Ground Zero intersection
- Lots of attention on this site
- Whichever tenant opens here will do gangbuster volumes
We were contacted by a regional coffee operator who was extremely persistent, engaged, and eager. Had a few conversations, and decided to visit his cafe and meet him in-person.
- Stunning, and I truly mean stunning, buildout.
- High energy.
- Extremely friendly staff.
Frankly, it felt like everyone was a Golden Retriever 🤣
Met the owner, and he was more passionate about the business than you can imagine. Extremely humble, but has that 'fire' in his eyes.
Asked him about why he got into the coffee business, and where he draws inspiration from.
He shares that Dutch Bros is the business model / strategy he favors the most, and can't stop raving about them as a competitor.
Cool. I agree - DB is doing something right.
Proceed to the next step - fully vetting the financials.
He sends screenshots of his portfolio - showing millions in account value.
Sorry - screenshots won't work for me.
Need full statements.
Sends me the account statements, and I start cracking up within 10 seconds 😅
$5M portfolio.
100% invested in Dutch Bros stock.
From a risk mitigation strategy - it's an absolute trainwreck:
- 100% of his personal income is derived from his coffee business
- 100% of his investment portfolio is staked in the coffee industry
From my perspective - this is the kind of psycho energy I love to see from an entrepreneur:
- 100% all-in
- 100% Ride-or-Die
Shared this update with my team - a few eyebrows were raised, but we loved it 😁
@Dudewithacigar
Off-brand, but I'll share some food for thought with respect to housing.
First off, the #1 priority should always be to increase housing affordability by creating new supply of housing. In the long-run, this outweighs everything else.
In the absence of increased housing supply, there are a few tools that can improve housing access.
I am a stark capitalist, but I do not think enough people are benefiting from the current system:
- A portion of our population is fully invested into stocks/real estate and is benefiting from the wealth created in our country.
- Another portion is entirely left out, and keeps falling further and further behind.
I am a strong believer that housing ownership is an incredible tool to maintain the 'American Dream' for all:
- 'Permanent' investment into the local economy (and a stake in its future)
- Tax benefits (e.g. interest deductions, capital gains)
- Passive wealth creation (home value increasing, principal paydown)
The reality is that housing has a cost associated with it. The payments will always exist - the question is where those payments are directed towards (rent vs. mortgage payments).
Many argue from a 2-dimensional perspective when it comes to 'rent vs own' - with the main metric noted being the payments associated via renting vs. owning. I do not think it's as simple as that.
Renting is great because it provides mobility and flexibility.
Housing ownership is even better due to the following:
- Financing a home is the most accessible tool to 'shorting' the US Dollar, which is effectively guaranteed to devalue over time (printing money)
- Payments are largely fixed - a $5,000/month mortgage today, is still $5,000/month in 15 years. Whereas, rent may be $4,000/month today and $6,500/month in 15 years.
- Highly leveraged return profile: most homes are acquired at 80% LTV. A 1% increase in the home value translates to a 5% return on equity; a 3% increase translates to a 15% return. This creates a stable path towards building your first $100k in equity quickly, which is an extremely important psychological milestone.
- Homeownership allows a borrower to benefit substantially from market gyrations. Mortgage rates today are +-6%. At some point in the next 10 years, I can almost guarantee that rates will hit 4% again or even close to 3%, which provides homeowners an ability to refinance the debt at a permanently lower interest rate. This 'optionality' does not exist in rentals; rental rates will always increase in the long-term.
- Homeownership permanently alters the dynamics of a voting base. When someone has nothing to lose, they will vote like they have nothing to lose. If shit hits the fan, they'll just pack their bags and move to a new City. When someone has a lot to lose (the value of their home), they will vote accordingly. Quite frankly, this is the most important reason, by far, to promote housing ownership nationally.
With respect to some of the 'tools' actively being discussed today, and hopefully some additional options:
- 50-Year mortgage
- Loan portability
- Property Tax portability
- Introducing the 1031 exchange for personal residences
50-Year Mortgage
Too many people are misunderstanding the impact of a 50-year mortgage because they are calculating its benefit based on current market conditions.
Don't forget what a mortgage is: each payment consists of interest expense and principal paydown, based on a certain amortization schedule.
At current 6% rates, $1M loan, the delta is miniscule:
- 30-Year Mortgage: $5,995/month
- 50-Year Mortgage: $5,264/month
12% savings in monthly payments.
At 3% rates, $1M loan, the delta is more pronounced:
- 30-Year Mortgage: $4,216/month
- 50-Year Mortgage: $3,220/month
24% savings in monthly payments.
This effect will be substantial in the right market environment, although it will also add substantial pressure on housing prices.
My preferred approach would be to reserve the 50-year mortgage for only 1st time home buyers. Let them benefit from this, and provide the younger generation an 'edge' they desperately need towards housing ownership.
The additional benefit is it increases the value attained of shorting the US Dollar. Principal payments are deferred into the future, which directly benefits the homeowner as the USD is devalued annually.
Loan Portability
Many homeowners are 'locked' into holding their existing homes simply because their mortgage payments will almost double if they purchase a new home today.
Create an avenue for a homeowner to take their existing debt on an asset, and apply it towards a bigger purchase.
This will provide an immediate avenue for cheaper housing inventory to enter the market, while these homeowners 'trade-up' into larger/bigger homes.
Property Tax Portability
Same commentary as above, but should also apply to property taxes.
Purchased a property 30 years ago with below-market property taxes? Transfer that basis over to your new purchase, but pay any increase in value difference.
For instance:
- Purchased a home 30 years ago for $200k
- Current tax bill is, for example, $5,000/year
- Current market value of the home is $1M
- Purchase a new home for $1.5M
Sell your home, and transfer your $5k/year property tax rate on the first $1M basis, and pay the market tax rate on the additional $500k value.
This will have the benefit of incentivizing 'trade-ups' into higher priced inventory, while allowing cheaper housing stock to enter the market.
1031 Exchange
The 1031 exchange has been the biggest financial boon for investment real estate.
Invest into property, and continue exchanging into larger and larger deals over time, with the expectation that the assets will transfer to your kids with no/limited tax burdens (step up in basis).
I simply do not see a reason why the average American shouldn't have access to this with their own personal residence. I'm fully aware of the $250k/$500k buffer on capital gains, but it should be uncapped.
Closing Thoughts
In the absence of effective housing policy that will create substantial new supply of housing, we can utilize financial policy to provide support/relief to homeownership.
These 'tools' are simply band-aids to alleviate the symptoms of governmental incompetence, but they are more readily attainable today as stopgap measures.
Want a great tip?
Always push for 270 day notice for exercising an extension option.
Most tenants will push for 120 - 180 notice periods, which Landlords always accept.
Why would you do that?
Think about the timing required to actually line up the next tenant:
- Sign a listing agreement with a broker
- Prepare marketing flyers / go live on the listing
- Generate tenant interest
- Filter, review, and negotiate LOIs
- Prepare a lease
- Negotiate a lease
- Engage architects/engineers/contractors, as needed, to deliver on the Landlord workletter
- Prepare plans and pursue permits
In the overwhelming majority of cases, you can't get all of this done in 120-180 days from start to finish.
So why agree to having only a 120-180 day lead time to find your replacement tenant? You're only guaranteeing a longer period of downtime between cashflows.
Ask for the 270 day notice period.
The tenants will always counter below this figure.
Hold firm, and you will get it.
If a Tenant is being particularly difficult about agreeing to the 270 days, then just use the following position:
"You will be operating at this location for 5/7/10 years before your option period kicks in. You will know damn well by Year 4, 6, 9 whether you want to continue operating this store or not."
That extra 3-5 months lead time is a 'free' 3-5 months of downtime you'll protect yourself against. It comes at zero cost to the Tenant, and puts money directly into your pocket.
I was invited to a poker game a few weeks ago, which was hosted today.
I met this gentleman through twitter, and we had lunch together. It was quickly apparent we would become good acquaintances/friends.
He invited me to play poker with his friends - a game I never played before (I don't gamble). I accepted, watched a few youtube videos, and arrived.
I never want to arrive empty handed:
- Brought one of my favorite whiskies
- Went to my cigar lounge and picked up a bunch of Cubans (in case it was a cigar-type event)
All the waitresses were crying when I dropped by, but nobody would spill the beans on what was going on.
I called one of my good friends (one of the hostesses not working tonight) on the way to poker night, and she had no idea either.
The poker night went great - great group of people, and a great environment entirely. I think they (seriously) doubted it was my first time playing, but it was, and everyone was helpful in explaining the game.
Received a text from my hostess friend - 'call me'
Said my goodbyes to everyone, got in the car and called her immediately.
Our friend was killed in a car accident after leaving a Halloween party.
I hate how life can change so drastically, for the worse, in the blink of an eye.
We lost a truly incredible person today. It hurts.
Take the time to appreciate your family and friends.
Take the time to visit your family and friends.
Ever heard the phrase 'chasing the dragon's tail'?
A local Developer took that phrase to heart, and rawdogged his life's work when interest rates collapsed in 2021-2022.
I have known about this Developer for nearly a decade. We're in similar networks, and often see each other at CRE events/dinners.
He is a very classy gentleman, but his appetite for risk is second-to-none.
Started off in a non-developer CRE role (vague on purpose), and began assembling development projects.
Success led by more success.
Solid doubles every time.
Payoffs that were multitudes of what he made working beforehand.
- Covid hits.
- Interest rates disappear.
- Exit cap rates approach <4% for absolute garbage new product.
Developer lines up ~30 developments in rapid order:
- Land acquired with hard money financing and minimal equity
- Soft costs funded with debt
- Construction costs funded with more hard money
Max LTV?
Doesn't matter - the sky is the limit 🥳🥳🥳
1.0% - 1.5% spreads?
Doesn't matter - there are no brakes on the gravy train 🚉
At underwriting - these deals were expected to net the Developer $40M+ profit.
Life. Changing. Money.
Fast forward to today:
- Cap rates have moved materially higher (STNL prices are down 20%+)
- Multiple tenants have blown out of the development projects
- Stated pro-forma profit is now closer to $2M (in my opinion, it's actually negative)
I'm going to give you the list of who made more profit than this Developer did on these projects:
- The land owners
- The leasing brokers
- The sales brokers
- The lenders
- The architects
- The engineers
- The attorneys
- The Cities (entitlement/permit fees)
Fuck - even the landscaper who trimmed his trees made more than he did 🙃
Why do Developer's 'make the big bucks'?
Because they do all the work, take on all the risk, and get paid last.
Sometimes (often) that means they make $0 when it's all said and done.
Partner asks me (last second) to join him in a meeting earlier today.
Two brokers are sitting in the conference room, and they're pitching to sell a development project we're wrapping up.
(these are for ultra luxury condos - not my cup of tea, but they are part of the legacy portfolio)
Broker #1 - a gentleman whose name I have heard spoken in the office. The main point of contact for discussions the last few weeks.
Broker #2 - the 'Rainmaker'
*****************************************************
How did I know Broker #2 was their office's rainmaker?
Google 'steepling'
I almost thought his fingertips were superglued together because he simply would not stop this pose for the entire hour🤣
*****************************************************
Broker #1 quickly introduces himself:
'Hello I'm XYZ and it's nice to meet you'
Broker #2 says 'I'm just here to lend support'
Those were the last words uttered from Broker #1 🤣
The 'rainmaker' just couldn't help himself, and took over the entire meeting from start to finish.
Granted, his pitch was actually phenomenal, despite knowing very little about the building itself.
I have seen this happen so many times before - the senior partner/director joins a sales pitch, and simply can't resist 'bringing the deal home'.
In lieu of giving the junior a chance to grow, the senior is too concerned with the risk of losing the business, and bulldozes the meeting.
Had this also occur last week on a retail deal we're considering selling - another Managing Director, who I never knew existed, joined the meeting and hijacked the entire sales pitch. In this case, it failed miserably, and we're giving the listing to another broker.
Want a great tip?
Give your juniors the opportunity to fail, learn, and grow - even if you are in the room when they fail.
Don't let the short-term results (a listing/transaction) impede on long-term gains (growing the capabilities of those below you).
Time kills deals.
Speed to deal execution can also leave money on the table.
So how do you create the sensation of speed and intensity in a deal, while slow-walking the rent negotiations?
Negotiating a 'deal' really has several parts to it:
- Deal economics (term, rent, TIAs, rent bumps)
- Delivery conditions (Landlord workletter)
- Misc. LOI provisions (lease commencement date, rent commencement date, assignment/sublease, etc.)
- Compensation (broker commissions)
- Optional Exhibits (site plan, floor plan, elevations, signage)
The vast majority of CRE investors will negotiate the core terms in an LOI at the same time (economics, delivery conditions, legal provisions, commissions). Very few will ever actually touch the exhibits until the lease is ready for execution.
I recommend the following structure:
- LOI Received
- Strikethrough the Rent and TIAs, and replace with "TBD - based on delivery conditions"
- Counter on the rent bumps, misc. LOI provisions and Landlord workletter first.
- Pay the maximum commission possible to the Tenant Rep broker. This should be resolved on Day 1 - get the Tenant Rep on your side.
Why are you negotiating the rent, TIAs, LOI provisions, workletter, etc. all at the same time?
Too many moving parts.
It's like juggling 6 apples at once, and hoping you won't drop any of them.
You're not a clown working at the circus - let's dignify this process.
Focus on isolating deal variables that drive value for you (neutralize the tenant-friendly provisions, reduce the workletter requirements, and push on maximizing rent increases, term, and guarantees).
Once the 'meat' of your LOI is approaching its final stages (usually by round #2), it's time for the next step.
Prepare deal exhibits immediately:
- Site Plan
- Floor Plan (with Landlord workletter items incorporated and annotated)
- Colored Elevations (with Landlord workletter items incorporated and annotated)
- Signage Exhibits (may be as simple as an already-prepared Master Sign Program or simply showing the tenant's signage on your colored elevations)
The creation of these exhibits is reducing risk for your tenant: they know the Landlord is serious about the deal, and they know they have a real, high probability site in front of them.
You want to get your counterpart invested into the outcome - the more they believe you'll deliver, the more they'll want this deal to happen.
Hint: do NOT cheap out on the quality of the exhibits you prepare. This is your first display to the Tenant of your expertise and professionalism.
Hire a skilled architect to prepare quality, detailed, clean plans that will present well.
Visuals are everything.
By the time these exhibits are completed, you should have also wrapped up the negotiations on the various LOI provisions + Landlord workletter items.
Send the exhibits.
Ask the Tenant to review.
Let them know you'll be preparing rent/TIA figures next.
By this point - you have done several things:
- Guaranteed a fat fee for the tenant rep
- Cemented the Landlord delivery costs
- Maximized deal value drivers (e.g. term, rent bumps, guarantees, etc.) prior to negotiating a rent
- Proven the viability of a likely deal, and your professionalism as a Landlord/Developer
- Created the 'sensation' of deal intensity and speed, without rushing through the rent negotiations
Give your LOI counter - the only redline should be in the rent/TIA figures, since everything else has already been negotiated.
I guarantee you - whatever rent you land at will be substantially better than if you had negotiated everything all together at the same time.
Good luck 🥳
A Tenant Rep broker applied a pretty sneaky tactic with me today. First time for everything 🥳🥳🥳
I have 1 remaining suite available in a Development project:
- Main & Main site
- Stunning redevelopment
- Restaurant AUVs in the market are un-fucking-believable
- Space being delivered in restaurant shell condition
Peak market comps point to X/SF.
3ND is quoting almost 2X.
I'm going to create a new watermark in the City, and I know the quality of my project.
I also know how to price leases based on expected restaurant AUVs.
Tenant Rep calls me and has a great tenant for the site - exactly the type of user I'm looking for.
We chat, and he transitions into the deal economics:
Tenant Rep: I spoke with your broker earlier, and he quoted me $13k/month all-in.
3ND: That doesn't sound right - should have been $13k base rent ($15k all-in).
Tenant Rep: No - I was quoted $13k all-in, which is already too high and unsupported by XYZ comps. Where do you think we can actually land?
(The rest of the negotiation doesn't matter - I know how to avoid negotiating against myself 😂)
Call wraps up.
I immediately dial my broker, and I'm not in a good mood.
If I want to quote a certain rent, I don't want my rep quoting a lower price to the market.
He picks up, and I ask him what rent he quoted the tenant rep broker: $15k all-in, with $13k in base rent.
Realize the tenant rep applied deception in an attempt to shake out how much room existed in the quoted rent.
I didn't take the bait, but I was very close (I know my quoted rent is high, and I am interested in the tenant).
It's really a sneaky tactic, in which the tenant rep broker has very limited downside ("oops - I thought he meant your quoted rent was the all-in rent, not the base rent"), even if he knows the truth.
The fact that he's using this approach means it works in enough cases to help shake out the true bottom line.
I've never experienced it before, but there's always a first time for everything.
Received an interesting call today.
I have a track record of some ground-up development projects in a certain city. The projects are all STNL, but people in the market - who know these sites - know they were very difficult to pull off.
- Receive a call from an unknown number.
- Picked up expecting to chat with a scammer 🤣
- He's calling on behalf of a local Developer in the market.
- Soliciting interest for one of the properties they own.
The call just felt slightly off. He's pitching a site, but he really doesn't sound like a broker.
Poked on this topic, and it comes out that he works in-house for the Developer.
Asked if he's responsible for acquisitions/dispositions.
Nope - responsible for securing debt and equity for their developments.
Asked for the property address, which he shared.
My left eyebrow nearly flew off my face when I pulled up the site 🤨
I know the property.
I know the Developer too. He's a legend.
The Developer is 'famous' in this City. He gets the royal treatment when he walks into City Hall. Responsible for some of the most notable completed, and planned, developments in this City.
I've kept tabs on his projects over the years (we have consultants in common). If any of them actually break ground, they will move the market.
The site being presented is phenomenal. Has some hair on it, but she's still beautiful 😂
The Developer has marketed the site on, and off-market, for about 3 years now. Always at a price that never made sense.
Told his employee I'm not interested at their price.
Shared the Developer is 'extremely motivated' 🤔
I've heard this before from so many brokers that I'm slightly desensitized to it, but it certainly hits different when someone in-house says it.
We shared some laughs regarding how shitty the City is to work with, and he slipped and asked me about a previous project I finished in the City (he knew the tenant, and the intersection).
I guess this call wasn't as much of a 'cold call' as I first thought.
I'm going to write an offer on the deal.
+- 1/2 their target price.
Why?
Several reasons.
#1) Developer has 3 major high rise projects in the City, which have approvals, but I'm estimating he doesn't have the funding to start.
#2) Developer is retooling inhouse personnel to keep them busy. This gentleman is purely responsible for raising debt and equity, but he's now being utilized to help instigate a sale transaction.
It's obvious something is totally off.
Said differently - at present time, the pursuit of raising capital via liquidating existing unproductive assets is a more viable outcome than raising capital via external sources. For a Developer with this guy's track record - this is a big deal.
#3) Attempt to save broker commissions by using inhouse team to consummate a transaction. This may be the best example of 'tripping over dollars to pick up pennies' that I have seen in a while.
Fun stuff.
I always share with those closest around me -
A great wife will make a man 100x wealthier.
Not because she may be an incredible businessperson.
Nor due to any investing prowess.
Simply because a good woman brings out the best in a man, and a good man brings out the best in a woman.
Among all the wealthiest and happiest families I know - they all have an incredible wife/mother in common.
It's not a coincidence.
Want a great tip?
IQ plays the greatest role in starting a negotiation, and EQ plays the greatest role in (successfully) concluding a negotiation.
Opening offers, and 1st round counters, are driven by strategy, logic, timing/cadence/pacing, etc.
Knowing how to apply pressure, when to apply pressure, and how much pressure to apply all evolve as you build your 'bank' of the deal's profile.
Each round of communication (email, text, call, meeting) helps build this bank of information you develop regarding your counterparties, and with how your counterparties are behaving in this specific deal.
Ever worked with someone on a deal before, and - for whatever reason - they appear more eager than usual to get a counter back from you?
Ever receive an email response from your counterparty, and an immediate follow-up from your counterparty's boss (before you could even respond)?
That's key intel on how that counterparty is behaving in a specific deal. It will also help you better understand how much value you can extract.
All great negotiations are maximized with EQ.
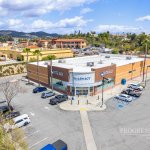
September 2021 - STNL building transacts in Wildomar, CA:
- Price: $8,400,000
- Cap: 6.20%
- Address: 32450 Clinton Keith Rd
Constantly growing trade area with affluent demographics.
Asset is purchased under a Trust. Implicitly, the Buyer thought they were purchasing a cornerstone coupon-clipper asset.
Asset hit the market for sale recently:
- Price: $5,900,000 ($342/SF)
- Occupancy: 0%
These vacant drug stores often hit the market at a high price - desperate sellers attempting to salvage their massive losses. This price, however, felt more aggressive than normal.
Looked up the transaction details - asset was acquired 65% LTV ($5,500,000 loan balance).
Owner is attempting to walk away with 'just' a 100% loss in equity. Realistically, their losses will be more as they continue carrying the asset - at a minimum:
- Mortgage Payments: ~$27,500 (monthly)
- Property Taxes: ~$7,500 (monthly)
- Insurance: ~$1,000 (monthly)
- Maintenance/Other: ~$1,000 (monthly)
Total minimum carrying costs: $37,000/month.
That's a burning hole in their pocket, and it hurts.
The reality is - their losses could have been entirely mitigated by doing a simple calculation before they purchased the property:
'If Rite Aid were to vacate tomorrow, then how much can I rent the space for?'
The answer - by all means - would have disqualified the purchase from ever happening.
This is a question you need to ask yourself any time you are pursuing a development or investment.
Assume the entire property is vacant, and you have to re-lease the building at normal market rates - will you be in a position where you can (at least) breakeven or, better yet, make a substantial profit?
