
Providing institutional-grade analysis, in-depth insights, and unbiased information to all participants in the digital asset industry. https://xitter.cf/t.co/ljTYqlhepa
Joined April 2018
- Tweets5.2K
- Following75
- Followers451K
- Likes682




Inflation is energy-led: CPI may peak near 3.9% in October, then ease to 2.6% by March.
🔸 AI demand and AI credit cooled in the same week
🔸 Dip-buying on Binance hit a record US$426M
Read full Binance Weekly Commentary ⬇️
binance.com/en/research/anal…

A closer look at #bStocks’ $1B milestone 👇
⚡ Fastest to reach $1B
🔄 More tokenized-stock transfer volume than all peers combined since its June launch
🔗 DeFi utilization consistently above the sector


Inflation is rising. The turning point may already be close.
September CPI reached 3.7% YoY.
The selloff was sharp. But higher energy prices and base effects had already set the stage for this rebound.
Here is the path our baseline suggests:
• October: the current inflation rebound could peak.
• Year-end: inflation stays elevated, with gradual cooling.
• March 2027: relief becomes more visible as spring 2026’s high energy prices enter the annual comparison.
This assumes energy prices ease and other CPI contributions remain steady.
Oil does not need to collapse for base effects to help.
The risk is another energy shock or renewed underlying inflation pressure.
For now, there is reason to look beyond the immediate scare.
The market is feeling the inflation squeeze. The window for relief may already be approaching.


Red hot CPI report fuels AI rout reut.rs/4zu65Zz reut.rs/4zu65Zz

The FSB's new report on global stablecoin arrangements notes that deep, liquid secondary markets could "help stabilise prices toward the peg."
Binance data offers one test. Across 127 BTC stress days since 2019, large USDC/USDT depegs have become rarer and shorter. On every day BTC moved ≥8% or swung ≥12% intraday, the time spent >20bp off peg fell from an average of 539 minutes in 2019–20 to 14 since 2023, under similar levels of market stress.
The order books behind this have deepened too: USDC/USDT depth within ±20bp hit a record in March 2026, a monthly median of $351M, 5.8x the 2024 median ($60M).
In practice, a large share of stablecoin exits might happen on secondary markets rather than through the issuer: in 2025, trading between stablecoins on Binance alone reached $769bn, versus $226bn of USDC redeemed by Circle, the only major issuer that publishes annual redemptions.


We have analysed the cross-border dimension of global #stablecoins from a financial stability perspective.
Read our short summary note to the #G20 to find out about potential cross-border vulnerabilities and the data that could support their monitoring: bit.ly/4rXVQu2

ALT The image shows a Financial Stability Board (FSB) publication titled "Global stablecoin arrangements." The cover features a globe design and is dated 12 October 2020. The background includes the blurred image of digital currency coins and financial data on a screen. The FSB logo appears in the top right and bottom left corners.
Manual order placement may soon be a thing of the past.
🔸 AI agents check the market 50 times before placing a single order
🔸 Binance AI beta users are 40% more likely to trade
🔸 Binance AI Pro beta users engage 30x more
Read more ⬇️
binance.com/en/research/anal…

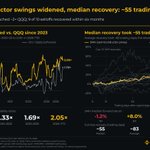
Semiconductor ($SMH) volatility relative to $QQQ has climbed from its 2022 lows to ~2×. Across 10 historical selloffs, recovery to recent highs took a median ~55 trading days—but the slowest took 369, about 18 months.
Buying the dip? Bring extra patience.


The recent pullback in AI hardware reflects renewed concerns over returns on massive compute spending, sparked by discrepancies in reported OpenAI revenue.
Higher real rates are also raising financing costs and weighing on valuations.
The prevailing market view is that the AI investment cycle will continue, with the next phase favoring enterprise software, data and cybersecurity platforms that can monetize AI.
Recent sector performance already shows this divergence.
Hardware’s ability to regain leadership will depend on further improvements in order outlooks and upward revisions to earnings forecasts.
Bonds are paying the most since 2008, while stocks are at record highs.
🔸 Only handful of AI-stocks are driving the rally, with lower valuation
🔸 Semiconductor inflows almost quadrupled
Read full Binance Weekly Commentary ⬇️
binance.com/en/research/anal…

The IMF finds most tokenized-stock trading happens off-hours. Our bStocks data says the same: 61.5% outside regular US hours.
Adding a few more data points to the conversation 👇


More than half of trading in tokenized equities takes place outside regular market hours. The demand for 24/7 access is real. The challenge is building markets that are also deep, liquid, and resilient. Learn more in our GFSR chapter on tokenization: imf.org/en/publications/gfsr…

$BTC has rebounded over 40% from July-bottom,
🔸 11.9 months past the peak, inside the 11 to 13 month bottom window
🔸 NUPL bottomed at 0.09 vs -0.31 in 2022
🔸 Golden cross in 2.3 months vs 3 to 6 before
Conviction, or a low still to come?
Read more ⬇️
binance.com/en/research/anal…


Time to explore Binance Monthly Market Insights.
🔸 Sep-2026: Strongest month for total crypto market cap
🔸 BTC confirmed a golden cross
🔸 Real yields weight on BTC
🔸 Pre-IPO perps volume on Binance doubled
🔸 bStocks utilization up to 11.2%, 3.8pp above sector
Read more ⬇️
binance.com/en/research/anal…

Time to explore Binance Weekly Market Commentary.
Key Insights:
🔸 Adjusted for volatility, Bitcoin’s 54.2% drawdown is a 1.94 standard deviation move, in line with the three previous bear markets.
🔸 A 47% bounce does not confirm the bottom.
Read more ⬇️
binance.com/en/research/anal…

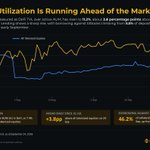
Tokenized equities are increasingly used on-chain, not just issued.
bStocks utilization has led the market since 31 Jul and now sits at 11.2%. Borrowing against bStocks has climbed to nearly half of collateral value.
The next benchmark is usage, not issuance.

Gemini 4 #Argon arrived after the US close on 30 Sep, alongside reports that staff questioned its benchmark scores versus real coding work.
@Google perp rose overnight, then reversed once US trading opened and ended the first day lower, its weakest day-one reaction among three releases since June. @Anthropic and @OpenAI perps also drifted lower.
Across new model releases since June, prices barely moved on day one, but over a week most moved further in the same direction.


👀 Rate expectations dropping fast. $BTC barely moved.
Futures-implied hike odds fell from 72% → 25% for October and 85% → 73% for December. BTC rose just 1.7% over the same period.
Could BTC be next to catch up? Drop your take below 👇

Two AI headlines yesterday.
@AnthropicAI's reported $42B annual loss: perp +0.19% in the first hour, −0.13% on the window.
@OpenAI's reported $70B run rate: +3.97%, +7.87% at peak.
Losses at this scale look largely priced in. Revenue growth less so.

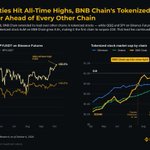
Tokenized stocks just crossed US$3B, and are rewriting the on-chain economy:
🔸 BNB Chain leads with US$1B in tokenized stocks and 1.8M holders
🔸 Q3 on-chain transfers topped US$100B
🔸 Tokenized stocks' DEX ratio hit 11% in September, closing in on memes at 17%
Read more ⬇️
binance.com/en/research/anal…

bitcoin:native faces renewed rate pressure with Treasury yields above 5%.
Yet 2026 ETF flows are back positive, while its golden cross came after 293 days below the 200-day average. Past deep resets varied, including 100-600% peak gains within a year.
Read on ⬇️
binance.com/en/research/anal…
