

8 Years Forex & Crypto Expert | 🌍 Macro Analyst | 🚀 Founder @GibhubPrime | 🔢 Numerologist | 💻 AI-Assisted Software Developer | ⛓️ Solidity Student
Joined April 2018
- Tweets15.2K
- Following1.8K
- Followers6.2K
- Likes30.7K



Pinned Tweet
Payout request approved
To get your own account use this link my.wemastertrade.com/registe…


Few minutes to our weekly space
🚨 GIBHUB ACADEMY WEEKLY X SPACES IS BACK!
We're resuming our weekly trading education sessions with a new series focused on helping traders understand the markets, improve their decision-making and develop consistency.
🎁 $15,000 WEMASTERTRADE INuSTANT FUNDED ACCOUNT GIVEAWAY!
3 winners. 3 days. $5,000 each!
We'll be giving away one $5,000 WeMasterTrade Instant Funded Account each day on Wednesday, Thursday and Friday.
📅 THIS WEEK'S SCHEDULE
🔹 SUNDAY, 15 NOVEMBER | 6 PM WAT
Weekly Market Outlook
Gold • Bitcoin • US30 • USD
🔹 WEDNESDAY, 18 NOVEMBER | 6 PM WAT
Trading Psychology (Part 1)
Understanding Trading Psychology: Why Traders Make Irrational Decisions.
- Fed FOMC Minutes Special.
🎁 $5,000 Funded Account Giveaway.
🔹 THURSDAY, 19 NOVEMBER | 6 PM WAT
Trading Psychology (Part 2)
Risk Management and Discipline: Learning to Control What You Can Control.
🎁 $5,000 Funded Account Giveaway.
🔹 FRIDAY, 20 NOVEMBER | 6 PM WAT
Trading Psychology (Part 3)
Building Consistency: How to Develop a Professional Trader's Mindset.
- PBoC Interest Rate Decision Special.
🎁 $5,000 Funded Account Giveaway.
We'll also explore how numerology can provide an additional perspective on personal behaviour, discipline, emotional tendencies and decision-making.
Expect practical discussions, market insights, fundamental analysis, technical analysis and real trading lessons.
⏰ TIME: 6:00 PM WAT DAILY
Come learn, participate and stand a chance to win a funded account!
GIBHUB ACADEMY × WEMASTERTRADE
#GibhubAcademy #WeMasterTrade #TradingEducation #ForexTrading #CryptoTrading


GIBHUB📊 retweeted

Every payout starts with someone who refused to give up. Meet today’s guest. ✨@fxqueen20 @gibhub189 @QingShiro
From Nigeria to a WeMasterTrade payout, this trader’s story proves that discipline beats hype every time. 💸
No fluff, no “get rich quick” promises. Just a real trader sharing a real result and the real process behind it.
👇 Drop a comment: What’s your biggest challenge in trading right now? I’ll be reading every response.
Most traders want access to bigger capital.
But here's a question:
Can you consistently manage the little capital you already have?
Before thinking about a $50K or $100K trading account, you should be able to demonstrate:
Consistent risk management.
Discipline in executing your strategy.
Control over drawdowns.
Patience to wait for quality setups.
The ability to follow a trading plan.
Capital is an opportunity. Your trading skills determine how well you use it.
This is why platforms like @WemasterAfrica are worth exploring.
They provide structured trading evaluation opportunities where traders can demonstrate their abilities using simulated accounts and potentially qualify for performance-based rewards.
Stop focusing only on how much capital you can access.
Start focusing on how well you can trade.
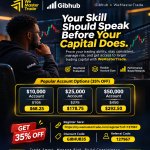
Your skill should speak before your capital does.
🚀 Explore WeMasterTrade
🔗 Registration Link: my.wemastertrade.com/registe…
🎁 Get 35% OFF using my discount code:
GIBHUB35
Referral Code: 127967
Trade smart. Manage risk. Build consistency.
GIBHUB × WEMASTERTRADE
🤖 Made with AI


📊 STOP GUESSING YOUR TRADING PERFORMANCE. START MEASURING IT.
Rather than guessing your average Risk-to-Reward (RR), win rate or percentage profit per trade, why not use a trading journal that actually shows you the numbers?
All you need to do is document your trades. GIBHUB JOURNAL evaluates your trading data and helps you understand:
• What you are doing right.
• Where your trading weaknesses are.
• How quickly you make money.
• How quickly you lose money.
• Whether your risk management is working.
• What needs improvement to become more profitable.
If you've been following me for a while, you'll notice that most of my setups target 1:10 RR, while my profit per trade is generally between 1% and 2%, mostly around 2%.
I didn't arrive at these numbers by guessing. I collected data, documented my trades and studied my performance using GIBHUB JOURNAL.
Right now, my focus is on improving three important areas:
Increasing my profit factor.
Reducing how quickly I lose money.
Increasing how efficiently I generate profits.
These are some of the things that contribute to long-term trading profitability.
And here's something many traders overlook:
Profitability is not just about having a good strategy. It's about having a system that measures, evaluates and improves your performance.
I call this THE MATH OF TRADING.
Trade with a plan. Document your results. Study your numbers. Improve your system.
Stop trading based on assumptions. Start trading with data.
GIBHUB JOURNAL — LET THE NUMBERS SPEAK.

🚨 A $862 BILLION DEBT MATURITY WALL IS APPROACHING, AND JPMORGAN WARNS THAT US CORPORATE LOAN DEFAULTS COULD MORE THAN DOUBLE IN 2027.
Could another major financial crisis be quietly building?
JPMorgan expects US leveraged-loan defaults to rise to 4.5% in 2027, up from 1.96% in October 2026. The rate could climb further to 4.75% in 2028.
But why is this happening, and why should markets care?
Three major risks are building:
1. Higher borrowing costs
Many companies borrowed heavily when interest rates were lower. With borrowing costs elevated, refinancing existing debt is becoming more expensive, putting pressure on companies already struggling with cash flow.
2. A massive debt maturity wall
Approximately $862 billion in leveraged loans will mature between 2027 and 2029.
More concerning, 46% of this debt carries a B3-or-lower credit rating, meaning many borrowers already have relatively weak credit profiles.
These companies may struggle to refinance when their loans mature.
3. AI disruption
Traditional software and technology companies face growing competition from AI.
As businesses adopt cheaper AI-powered alternatives, some software companies could lose customers, revenue and profitability while still carrying significant debt.
WHY DOES THIS MATTER FOR THE WIDER ECONOMY?
If defaults increase, lenders could become more cautious, making credit harder and more expensive to obtain.
That could reduce business investment, trigger layoffs and weaken economic activity.
JPMorgan also expects high-yield bond defaults to rise more modestly to 2.75% in 2027.
THE 2008 FINANCIAL CRISIS CONNECTION
The 2008 Global Financial Crisis was triggered largely by excessive lending in the US housing market, particularly subprime mortgages.
When borrowers began defaulting and housing prices collapsed, financial institutions suffered massive losses. Credit markets froze, major institutions failed or required emergency support, and the crisis spread across the global economy.
What is similar today?
The common thread is excessive leverage, risky borrowing, debt repayment difficulties and the possibility that financial stress could spread beyond the original borrowers.
In 2008, the problem started in the mortgage market and spread through the banking system.
Today, the concern is whether corporate credit stress could spread through leveraged loans, private credit, institutional lenders and the broader financial system.
The situations are not identical, but the similarities deserve attention.
MY PERSONAL SPECULATION: COULD A FINANCIAL CRISIS BE COOKING?
I don't think investors should dismiss the possibility of another major financial crisis developing.
We have rising corporate debt risks, refinancing pressures, technological disruption and growing concerns about the stability of parts of the financial system.
My bigger question is what happens if confidence in traditional financial institutions begins to deteriorate.
Could this accelerate the movement towards blockchain-based financial infrastructure?
My speculation is that a major crisis of confidence in the traditional financial system could push more people and institutions to explore alternatives such as:
• Bitcoin as an alternative monetary asset.
• Stablecoins for digital payments and dollar access.
• Decentralised finance (DeFi).
• Tokenisation of traditional financial assets.
• Blockchain-based settlement and financial infrastructure.
This does not mean blockchain or crypto would automatically be safe during a crisis. They carry their own risks.
However, a loss of confidence in the traditional system could strengthen the argument for alternative financial infrastructure.
WHAT SHOULD INVESTORS WATCH?
• US high-yield credit spreads.
• Leveraged-loan prices and default rates.
• Corporate refinancing activity.
• US Treasury yields.
• Federal Reserve interest-rate expectations.
• AI disruption across software and technology.
• Bitcoin and stablecoin adoption.
• Signs of tightening credit conditions.
THE BIGGER PICTURE
The real concern is not just the amount of debt approaching maturity. It is whether companies will have the financial strength to repay or refinance it.
If defaults accelerate and lenders begin restricting credit, the consequences could extend beyond struggling companies and affect investment, employment, economic growth and financial markets.
We are not necessarily heading for another 2008, but I believe the possibility of significant financial stress deserves serious attention.
And if confidence in the old financial system weakens, blockchain could become one of the biggest beneficiaries of that shift.
What do you think? Are we seeing the early signs of another major credit crisis?
GIBHUB MACRO INTELLIGENCE
Numbers Reveal Patterns. Wisdom Creates Destiny.

2
235


