

dotData Feature Factory technology provides data-centric & programmatic feature discovery for data scientists & data engineers.
California, USA
Joined May 2019
- Tweets453
- Following42
- Followers267
- Likes19




Subventions hide bad pricing. A promo contract looks profitable only because the manufacturer pays the gap.
The test: back-test promo loans without subventions to find underpriced tiers, the same ones pricing today’s standard book.
Read the analysis ⤵️
#Lending #RiskManagement


Blended averages hide major auto lending risks. Prime 60+ DPD is 0.42% vs subprime at 6.90%, a 15x risk gap lost in portfolio averages.
Is your software missing critical risk signals?
Read how to spot flaws in your next vendor demo 👇
hubs.ly/Q04BdFsz0

Yokohama Rubber and dotData Begin Joint Development of an AI Agent for Manufacturing R&D
Read the announcement 👇
hubs.ly/Q04zYj-F0
#Yokohama #dotData #AIAgent #AIforManufacturing

Read the full press release: dotdata.com/news/pressreleas…

Shrinking auto loan volume with stable charge-offs? You might be overpricing.
83% of auto loans are indirect if your buy rate is too high, dealers just send the deal elsewhere.
Pair look-to-book with tier losses to catch the leak.
Full analysis 👇
hubs.ly/Q04zp4V40


Tier-level pricing treats every borrower in a band the same and edge-of-tier mispricing is costing auto lenders.
dotData uncovers the Driver Signals that explain why actual losses diverge from forecasts, without a model rebuild.
Fix your rate sheet ⤵️

Read the full post: dotdata.com/blog/loan-pricin…
NCO rates reflect underwriting decisions made 18-36 months ago.
With LTVs over 120% and repo recoveries near 30%, waiting for charge-off reports means acting too late.
Learn how to flag high-risk accounts 6-12 months early 👇
hubs.ly/Q04ywYqp0
#CreditRisk #AutoLending

Read the full post: dotdata.com/blog/auto-loan-c…
A 50% default rate in 0.4% of your auto portfolio won't move your aggregate average, but it will eat your margins.
Risk doesn't spread evenly; it concentrates in blind spots.
See how signal stacking exposes hidden risk in booked loans 👇
hubs.ly/Q04xWSb70
Read more ⤵️

Read the full blog here: dotdata.com/blog/ai-based-po…
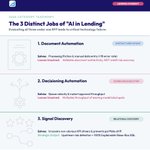
Most auto lending risk leaders fail before the software demo even starts.
Evaluating fraud filters, decisioning engines, BI, & Signal Intelligence under one label creates winners by accident.
Fix your risk evaluation process 👇 hubs.ly/Q04xJBJB0

